

What changes in Gross Income Tax in Santa Fe with the fiscal agreement and the Santa Fe SME Law, and on what economic structure is the tax collection based? March 2018 report.
On May 1st, the Governor of the Province of Santa Fe will deliver the address that will inaugurate the province's legislative year. As is customary, the head of the Executive branch is expected to review his administration's achievements and outline the general guidelines for the coming year.
However, beyond the various projects that can be implemented by the ruling party or those that can be contributed by the opposition, there is an economic limit to their implementation within a given timeframe. This limit is determined by the resources the province receives and the organization's capacity to manage them. State capacity is, in itself, a resource.
Regarding this point, the report presented in this edition outlines the economic structure of the province of Santa Fe . In other words, it describes the context in which economic activity takes place. From this structure, the various levels of government extract resources through taxes to fund state activities.
As usual, one of the biggest limitations for writing the report is the lack of systematic or up-to-date statistical information.
To solve this issue, alternative sources of information have been used, which, although not perfectly compatible with each other, allow us to get around the problem, until common trends (or, at least, not incompatible ones) are detected.
Consensus for Santa Fe
The national government reached a fiscal agreement with almost all the provinces (except San Luis) . This agreement establishes guidelines for resource allocation and a commitment to reduce spending and taxes. The Province of Santa Fe joined the Fiscal Pact in February of this year through Provincial Law 13.748, published on February 19 in the Provincial Official Gazette.
One of the important aspects of this negotiation is the following. The fiscal agreement allows the province to demand a proposal for the payment of the historical debt owed by the national government. This debt originated from the improper withholding of shared revenue funds. However, in November 2015, Santa Fe obtained a favorable ruling from the Supreme Court of Justice, although it has not yet been enforced.
In general terms, the national government seeks to alleviate the fiscal deficit problem at both the national and provincial levels. Its strategy relies on the tax system, which presents the following dilemma: reducing the tax burden (and, consequently, government revenue) to increase business activity (and thus increase tax collection).
For example, for 2020 the fiscal consensus provides that several branches of activity will be exempt from provincial gross income.
The debt dilemma and the commitments of consensus
However, this dilemma is compounded by another dilemma regarding resources. To cover the cost of the proposed tax reform, debt is being taken on to address the resulting imbalances. These imbalances stem not only from the fiscal problem itself, but also from the numerous other challenges facing the country.
Taking on debt comes at a cost in the form of interest payments. Therefore, the widespread use of this instrument creates a new dilemma: the speed of implementation of the various strategies organized from the current perspective of the national government.
The agreement takes effect this year and must be fulfilled before December 31, 2019. It includes the enactment of several national laws and, perhaps the most complex objective, reaching a consensus on a new federal tax revenue-sharing law.
Meanwhile, the provinces are committed to modifying the gross income tax, property tax, stamp tax, payroll taxes, municipal taxes, and other specific taxes.
The weight of Gross Revenue in tax collection
These changes are expected to affect provincial government revenue. The Gross Income Tax (IIBB) is the main source of provincial revenue. In 2017, it represented 25,28% of the total resources of the Santa Fe provincial government, including those received through national revenue sharing. Projections for 2018 estimate a share of 26,64%.
Furthermore, the resources obtained by the province from this tax reached 79,88% in 2017 and 78,42% in 2018 of the province's tax resources.
Under the tax agreement, it is anticipated that—for example—by 2020, three sectors will be exempt from the Gross Income Tax (IIBB). All of these belong to the primary sector. Meanwhile, the two sectors with the highest tax rate (6%) would be financial services and mobile telephony.
So, on what economic structure is the tax regime change being implemented? The report, attached to this note and available for download, explains the composition by productive sectors and their relative weight in generating added value. It does so for the economy of the Province of Santa Fe in general, and for the Greater Rosario Metropolitan Area (AGR) in particular.
Gross Income tax rates in 2018
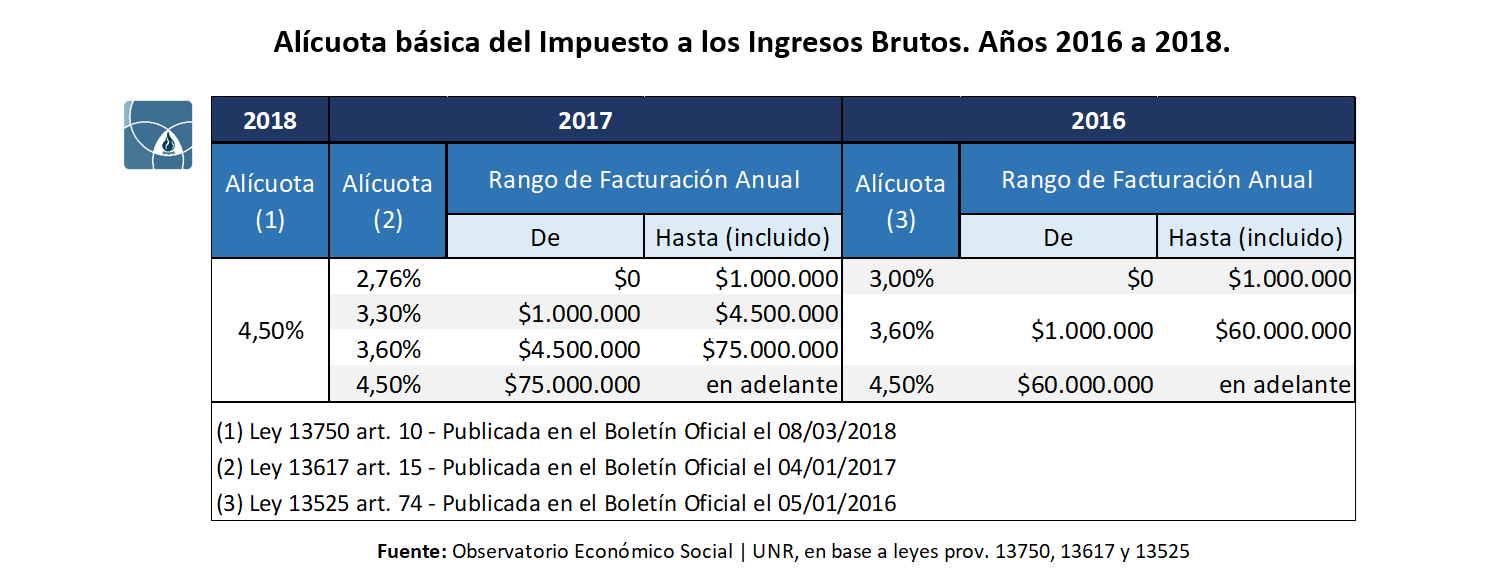
The table below shows the changes to the basic tax rate for the current fiscal year. The comparison is made with 2017 and 2016. As can be seen, the basic tax rate for 2018 is 4,5%, regardless of the company's revenue. This is equivalent to the maximum tax rate of previous years. In other words, in terms of the basic tax rate and compared to 2017, the province increased the IIB (Income Tax on Gross Income).
In contrast, these amounts can only be implemented once the Santa Fe SME Law comes into effect . Through this law, the province adheres—with modifications—to the tax stability regime of National Law 27.264. This means that companies categorized as SMEs receive a set of tax benefits, encompassing a wide range of taxes, including the Gross Income Tax (IIB). Thus, the overall increase is offset by the tax benefits that SMEs in the province receive.
What happens to those sectors of activity that have special or specific tax regimes? Provincial Law 13750 shows no major differences in this regard. Some general industrial activities, as well as meat processing and sales, go from being taxed at a rate of 0,5% to a higher rate of 2%.
The same applies to other industrial activities such as grain and oilseed processing or contract manufacturing. These activities will now be taxed at 2%, up from 1,5%. Furthermore, the decree updates the taxable amounts (but not the tax rates) for the revenue brackets related to gaming and leisure activities.
Small taxpayers and SMEs
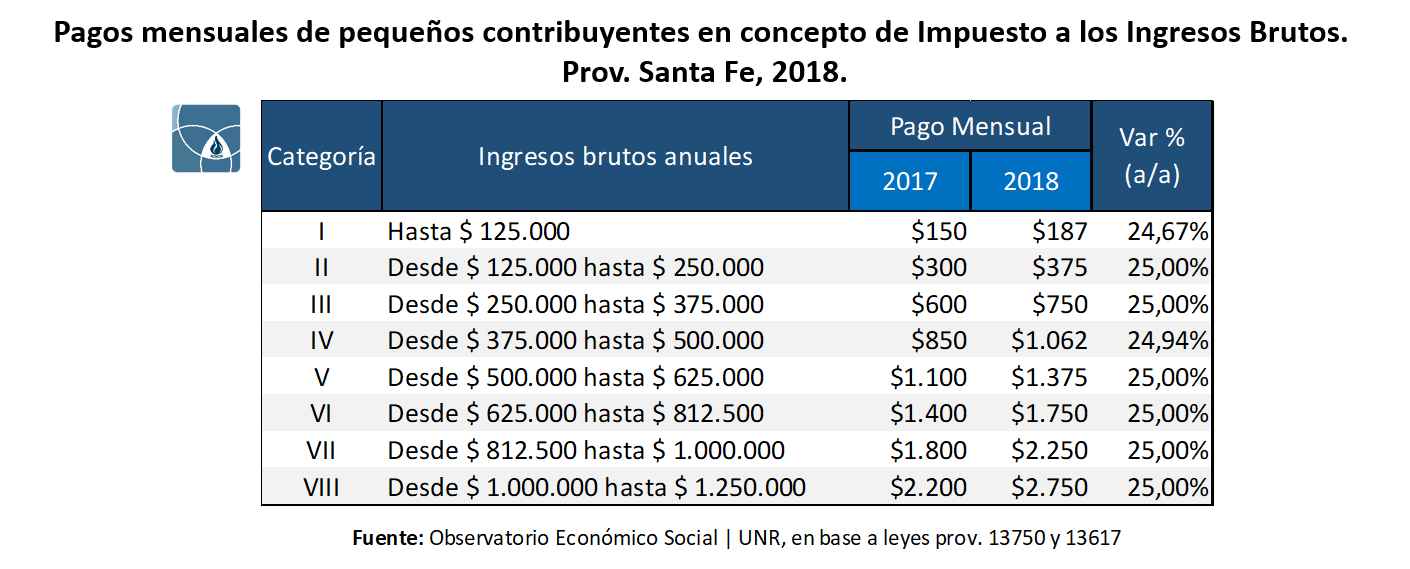
Small taxpayers will not benefit from the 2018 regulations . The table below shows an average year-on-year increase of 25% for monthly payments across all categories. This increase is essentially in line with the inflation rate recorded in 2017. However, the taxable revenue brackets remain unchanged.
In this sense, any taxpayer who is in the intermediate level of their category (with the exception of I) and adjusts their billing to a minimum level of 25%, should be forced to recategorize to a higher level in the next fiscal year.
Finally, the directly identifiable beneficiaries of the new tax regime configuration are the so-called SMEs.
Although the set of measures is broader than that which is addressed in this article, with regard to the IIB (and also the Stamp Tax) adherence to the fiscal stability regime provided for in article 16 of National Law 27264 is counterbalanced by the commitment on the part of the provincial government not to increase the amounts of the rate until December 31, 2019.
In order to obtain a more complete overview of the configuration of the economic structure of the province of Santa Fe, and on which the imposition of the tax regime affects, we invite you to read the report that we make available to you.
Open access, for use and citation
The report is available freely and without charge, under a Creative Commons license (CC BY-NC-SA 4.0):
- 📄 Full report (PDF): Download the report
- 🗄️ UNR Hypermedia Repository (RepHip): https://hdl.handle.net/2133/17517
- 📚 More reports from the Observatory: Index of Reports
Santa Fe 2018: fiscal y estructura económica. Informes del Observatorio UNR N.º 42 — Serie Informes de Coyuntura N.º 14, marzo de 2018. ISSN 2683-9067 / 2683-9075. Autores: Germán A. Tessmer, Patricio H. Almeida Gentile y Luciano A. Jara Musuruana.