


Yesterday, the first round of public hearings regarding the adjustment of gas energy tariffs concluded. In this report, we provide a brief overview of the sector and future prospects, with explanatory notes on the concepts used in this entry.
Protection as a strategy
The Supreme Court ruling that rolled back gas rates to their 2015 levels forced the national government to devise a new rate increase plan for this year. The government's proposal was published on the Enargas website prior to the round of public hearings scheduled for the weekend of September 16, 2016.
It proposes a gradual increase in the price of gas paid to producers, which at first will be considerably lower than the initial proposal, but which in the medium term (2020) will gradually converge to USD 6,8 per MBTU as shown in the following table:
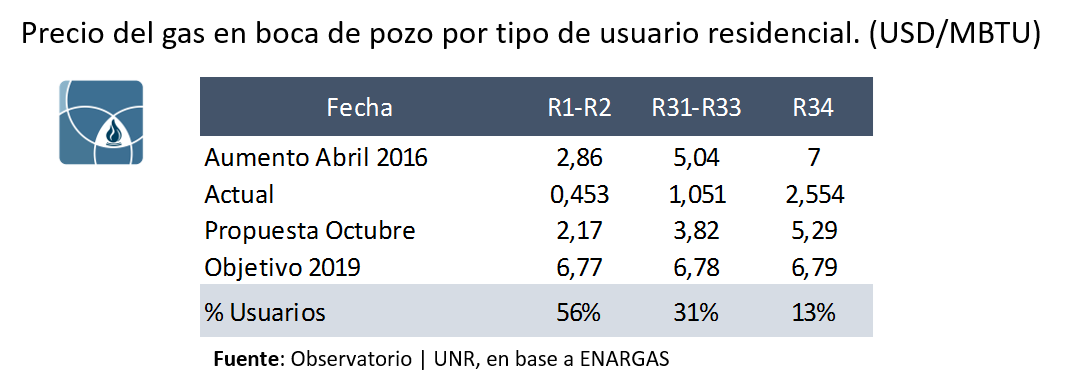
What is the justification for setting a target of 6,8 USD/MBTU in the long term? It's pretty simple. This is the maximum price paid for the import of gas by ship, including the cost of regasification (the latter, because the import by ship is in the form of liquefied gas).
In technical terms, the goal is to bring natural gas prices in line with the marginal cost of market supply.
Economic logic indicates that, at least with inelastic demand, this could be the market price of gas if it depended on the free play of supply and demand.
In fact, it could even be argued that during the winter months natural gas has a higher price, given that gas scarcity and infrastructure limitations prevent the market from being fully supplied with gas and electricity plants must generate part of the energy with even more expensive fuels, such as diesel, whose price exceeds 11 USD/MBTU.
Current situation
The high marginal cost of supplying the market is a consequence of the energy policy implemented over the last decade. In 2002, gas prices were pegged to the peso and frozen, without the establishment of a long-term adjustment mechanism.
With the depreciation of the peso and the rise in international fuel prices, this led to their prices falling behind the international level, reaching more than 60% below the import cost. As a result, investment in the sector has plummeted and production has contracted by 16% in the last decade.
Likewise, as demand continued to increase in line with economic and population growth, and without promoting the replacement of natural gas with other energy sources; This quickly generated a supply deficit.
Consequently, and conditional on the fact that Bolivia's natural gas import possibilities are limited, the country had to resort to the use of LNG or liquid fuels, which are much more expensive. Under this scheme, the cost of energy - largely subsidized by the state - became increasingly higher.
Tariff scheme update
The current tariff scheme seeks to correct some of these errors, setting a price more related to market mechanisms (although without ceasing to be regulated), probably more attractive for investment and with a long-term path in dollars and, therefore, less subject to erosion by inflation.
However, it is precisely because of the current situation that it is not logical to take the marginal supply cost as a reference for all demand.
Although 6,8 USD/MBTU is the cost of importing LNG, the production cost of the rest of the supply is much lower. Thus, setting this price for local natural gas implies the transfer of a significant income from consumers to oil companies, to a greater or lesser extent depending on the type of field in question.
According to YPF presentations, the cost of gas extraction (including investment in exploration and an annual return on capital of 13%) is currently located at 5,0 USD/MBTU.
Beyond this, from the most orthodox economic theory this scheme could be perfectly defended. After all, if the lawsuit validates a price of 6,8 USD/MBTU, companies could charge it.
After all, isn't this what happens in other markets with inelastic demand? Yes, but there are two reasons why the situation is different in the case of natural gas.
• First, hydrocarbon companies exploit a resource that belongs to all Argentinians. It is not a good created by them. Therefore, an appropriate policy should aim to maximize the income obtained by consumers (or the national government) in the long term.
This implies encouraging supply and providing adequate prices to encourage investment, but also balancing the impact on consumption given that, without income, said energy would not be generated. After all, what is the advantage of having natural gas resources if it ends up costing more than what Japan must pay to be supplied with LNG? In countries that have greater energy resources, they are cheaper and this is an advantage for their industry and their population. Not only an advantage for the companies that exploit them.
• Secondly, the justification of the traditional theory depends crucially on the action of competition, according to which, if there were a way to produce these goods at a lower cost than what demand pays, this would encourage supply and would reduce the price. This is indeed a possibility in the case of Argentine gas. But it must be considered that these mechanisms have not operated for the last thirteen years.
Thus, the marginal cost is so high precisely because supply had no incentive to respond. Switching to a scheme like the one suggested when supply cannot respond quickly (as happens in gas production) will always imply an initial period of extraordinary profits for the producer. In other words, past distortions generate an artificially high profit for the new investor.
Final comments
Thus, and considering the above, there is one way to understand the government's proposal . This is a productive development policy that seeks to develop industry by initially incentivizing high prices. In other words, the system that is being dismantled for the textile and electronics industries (which have benefited for years from strict import restrictions) is being implemented for the oil industry.
It is true that there are important differences between the two types of industry. Energy plays a strategic role for the country's development, and Argentina's possibilities to reduce production costs are much greater in the case of gas than in the protected sectors during the last decade, in which it seemed very difficult that they would even come close to import parity.
But there are not so many differences in the way the policy is applied, which repeats all the usual errors of Argentina's protectionist policies: unconditional benefits without demands or punishments for companies.
Regarding the latter, a modification that has emerged from the public hearing concluded on Sunday, September 18, which represents a novel aspect, and a counterpoint to what was expressed in the previous paragraph: the government will not allow companies to transfer dividends abroad. gas companies as long as they do not comply with their investment plan and that, even if they are executed, they must have the authorization of Enargas, for this purpose.
Likewise, the final regulation and adaptation of these points is estimated to take place in the general public hearing to be held in the second half of October.
Recovering natural gas production must be a strategic objective of the national government, and it is undeniable that this requires a clear price path, significantly higher than those in place over the last decade. However, simply recovering production cannot justify any domestic price. Otherwise, the advantages of being a country rich in gas (both conventional and unconventional) will accrue only to the companies that extract it.