

What effects did the currency controls have on reserves, the monetary base, and the parallel exchange rate between 2011 and 2015, and what could be expected from the removal of these controls? December 2015 report.
A good way to think about money is to compare it to water flowing through a leaky pipe. If the water flows strongly, some of the pipe walls may be damaged, creating leaks. These leaks divert the liquid to unintended locations, contrary to the design of the pipe.
In this way, one risk is that the circuit dries out, another that the water stagnates.
Originally intended to mitigate capital flight, the first measure aimed at imposing currency controls dates back to October 31, 2011. On that date, AFIP began issuing authorized purchase permits, and pressure was put on companies to reduce their imports.
Continuing with our metaphor, the aim was to correct the water circulation pressure, which was going to dry out the system. To achieve this, a valve was installed, to be operated by the Central Bank.
The problem is that by doing this, the pressure only decreased on one side. On the opposite side of the valve, the pressure had to be supported by the rest of the circuit.
Leaks and cracks: the blue dollar and the cash with liquidity
What did this pressure consist of? It consisted of excess demand pushing to acquire more dollars at the official exchange rate. Logically, when the currency price fell below the equilibrium price, a leak emerged: the black market to supply the demand of small savers at its corresponding price, the blue dollar.
But a fissure also opened up: the flight of foreign currency abroad by companies through the intensive use of buying and selling bonds that are quoted in dollars and are susceptible to being traded abroad, also with their corresponding price, the cash settlement.
The consolidated information in our monetary report is from July of this year. At that time, there were no indications that a change in the national government's administration was imminent. Even less indication was there any sign that the currency controls would be lifted on December 17th.
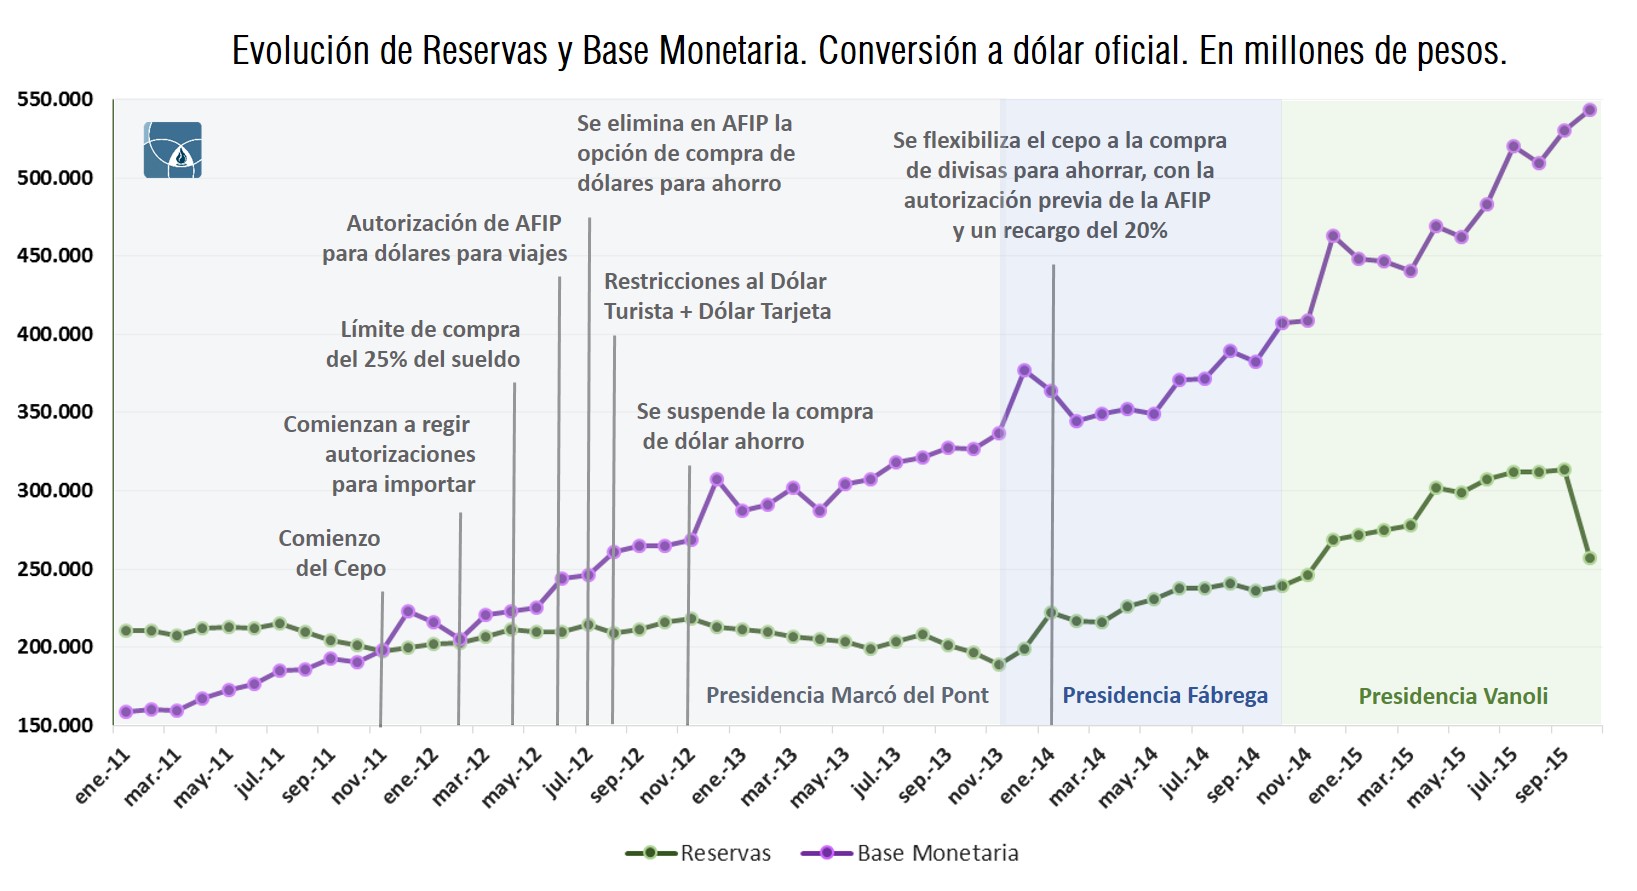
However, what the data clearly shows is the strong pressure that Treasury financing exerted on the Central Bank. This led to a subsequent expansion of the monetary base, meaning the injection of a larger amount of pesos into the economy's money supply.
Monetary base and reserves in July 2015
Indeed, at the end of July, the monetary base stood at around $520.170 billion. This represents a year-on-year increase of 39,95%, well above the average year-on-year growth rate for 2015.
In other words, the month of July not only ratifies the long-term tendency exerted against the exchange system by the public, but also that it is a month where this pressure is accentuated due to the lack of sterilization measures.
Note that in the chart above, reserves are expressed in millions of pesos. Even so, the gap between the two series has been widening month by month.
What is the point being made by the above? To construct the series, the Central Bank's dollar reserves were converted to pesos at the official exchange rate in effect at the end of each month. In other words, the reserves (in dollars) were multiplied by the exchange rate month by month.
In a context where exchange rate policy followed an upward crawling peg pattern , much of the series' growth is explained by increases in the exchange rate. It should also be noted that this trend acquires a positive slope after the January 2014 devaluation, of around 17% depending on the reference period.
many valves
Lately, history has been heavily invoked as a source for interpreting current events. Strikingly, one fact that hasn't been mentioned much in this week's public debate is that since the 50s, Argentina has had several experiences with multiple exchange rates, which—in retrospect—were not positive.
Ultimately, they generated an increase in the assets of Argentines abroad.
In general, when multiple exchange rates persist long enough for agents to generate strategies to arbitrate between the different prices of the currency, international transfer systems are created with the aim of maintaining stocks of foreign currency in foreign accounts. , or to be negotiated in the local free market segment, obtaining significant profits with detriment to the national economy.
Furthermore, speculation is not only financial. Multiple exchange rate systems have generally led to over-invoicing of imports and under-invoicing of exports.
In previous paragraphs we mentioned that the imposition of the exchange controls provided a strong incentive for different types of agents to satisfy - even if only partially - their demand for dollars.
But the story doesn't end there. Argentina's tax system also generates different exchange rates that agents use as a reference depending on their sector.
The different prices of the dollar
In this way, until before exchange rate unification, the country had the following currency prices:
Official Dollar: This is the dollar value published by the Central Bank of the Argentine Republic (BCRA).
Blue Dollar: This is the transaction value of the dollar on the black market. As we stated in previous paragraphs, this term began to be used in the country in 2011, due to restrictions on the purchase of foreign currency imposed by the Federal Administration of Public Revenue (AFIP) and the Central Bank of the Argentine Republic.
Cash Settlement: also known as the gray dollar, the flight dollar, or simply the stock market dollar. This is the method companies typically use to move funds abroad through the purchase and sale of bonds. The procedure involves acquiring Argentine government bonds issued in dollars, such as the Boden 2012, Bonar X, or Boden 2015, which are traded on the New York Stock Exchange. A financial institution opens an account abroad, to which the asset is transferred. The transaction is then settled in cash (hence the name) abroad. These dollars are credited to the account created outside the country.
Tourist dollar, savings, soybeans and future
Tourist Dollar: also known as the credit card dollar. This is the rate resulting from adding a 35% surcharge to the official dollar exchange rate. This surcharge is imposed by the AFIP (Argentine Federal Public Revenue Administration) on purchases made with credit and debit cards abroad. The same mechanism applies to online purchases from foreign websites.
Savings Dollar: After two years of prohibitions, at the beginning of Juan Carlos Fábrega's presidency at the Central Bank, the Argentine government again allowed the purchase of foreign currency on the official market, subject to a series of conditions. Buying dollars at the official exchange rate was permitted with up to 20% of declared monthly income, with a maximum limit of US$2.000. If the customer wished to obtain the dollars in cash, a 20% penalty was applied to the official exchange rate. However, if the currency was deposited for one year in a commercial bank, the penalty was waived.
Soybean Dollar: This is calculated by taking the official dollar exchange rate and subtracting the export taxes levied on the product. In other words, it represents the profit in dollars that soybean producers receive after the government applies the relevant taxes. There are also variations such as the sunflower dollar and the wheat dollar.
Dollar Futures: A futures contract is an agreement to buy or sell an asset at a future date and a predetermined price. At expiration, the seller (buyer) makes a profit (loss), depending on whether the price is higher or lower than the agreed-upon price.
Generic positions regarding unification
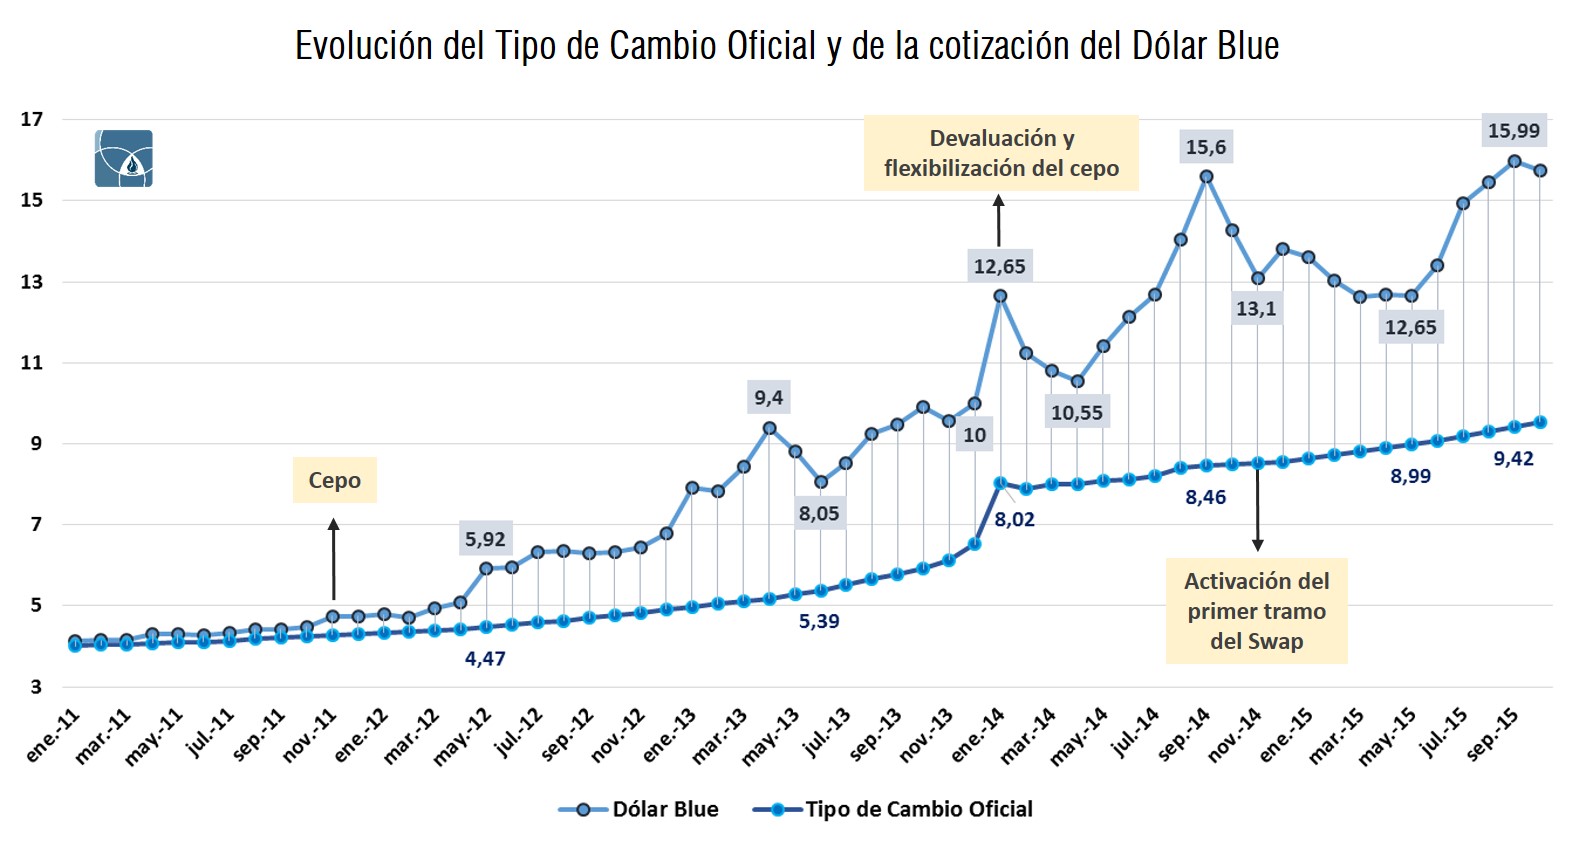
As we always mention in our reports, in economics every benefit has its cost. The following graph shows the evolution of dollar-denominated reserves and the official exchange rate. As can be seen, the rate of reserve loss month after month has been practically constant since the beginning of the reported series. But this trend not only persists, it intensifies with the first implementation of capital controls.
Only after the devaluation of early 2014 did the level of reserves stabilize. Subsequently, it was maintained through the various executions of the swap tranches with China.
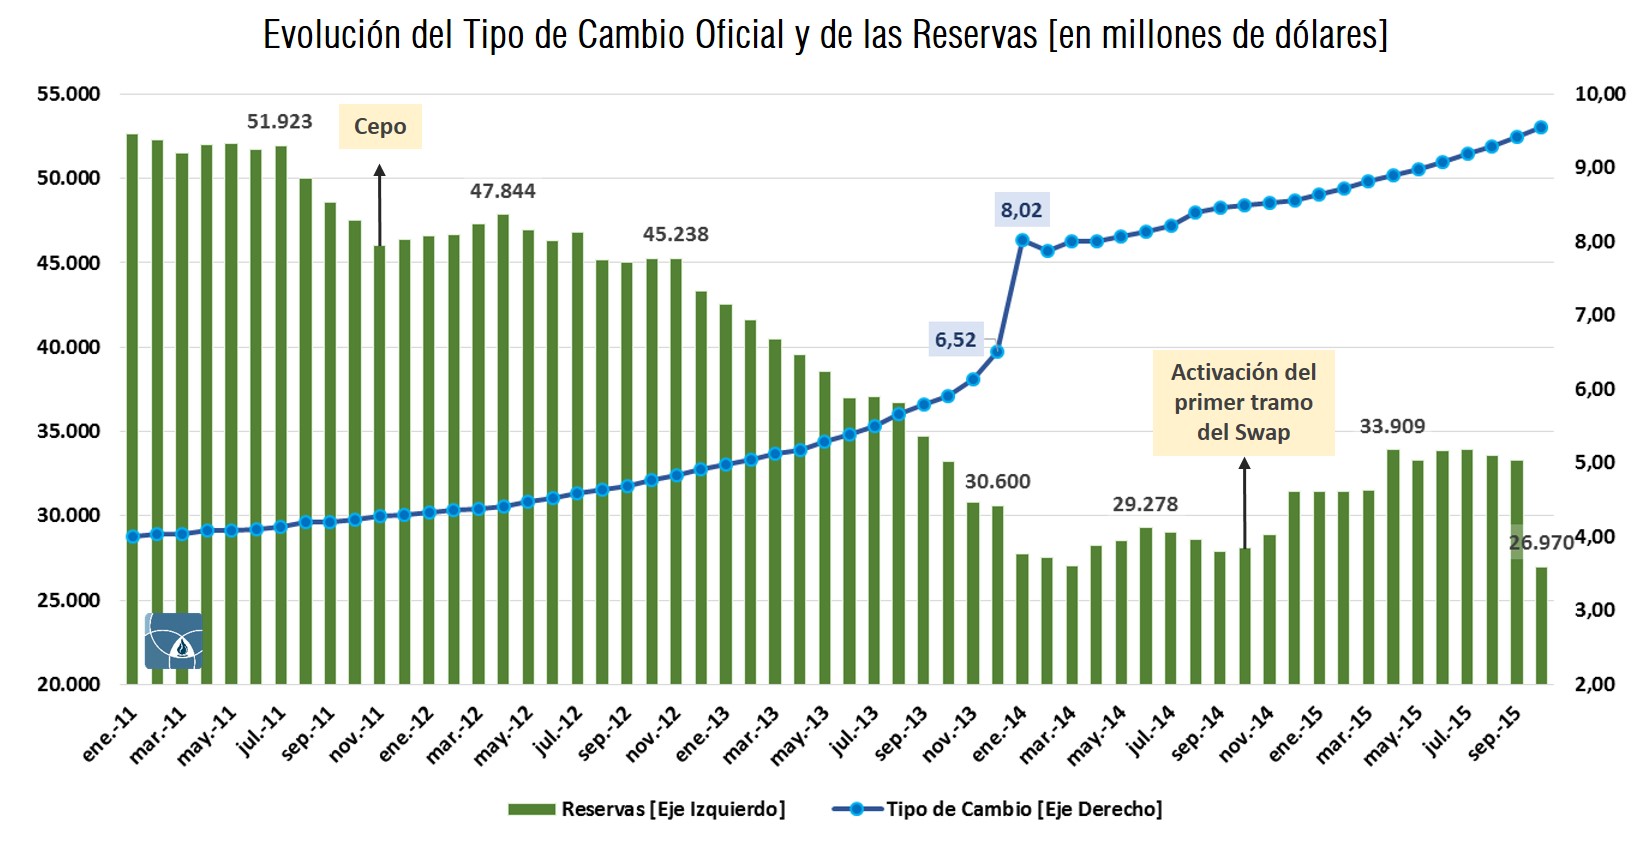
When rigorously analyzing the success of the currency controls, the graph above is not the best indicator. Strictly speaking, a counterfactual would be needed to complete the analysis . That is, a similar graph estimating what would have happened if the various measures had not been implemented.
Or better yet, several counterfactual scenarios that reflect the behavior of the series under different economic policy measures. Unfortunately, we do not yet have the technical capability to conduct randomized controlled experiments on macroeconomic issues.
Therefore, our analysis must focus on the observed series. Note that both with the implementation of the exchange controls and with the devaluation and easing of restrictions in 2014, reserves reacted positively during the four months immediately following the measure, before resuming their downward spiral.
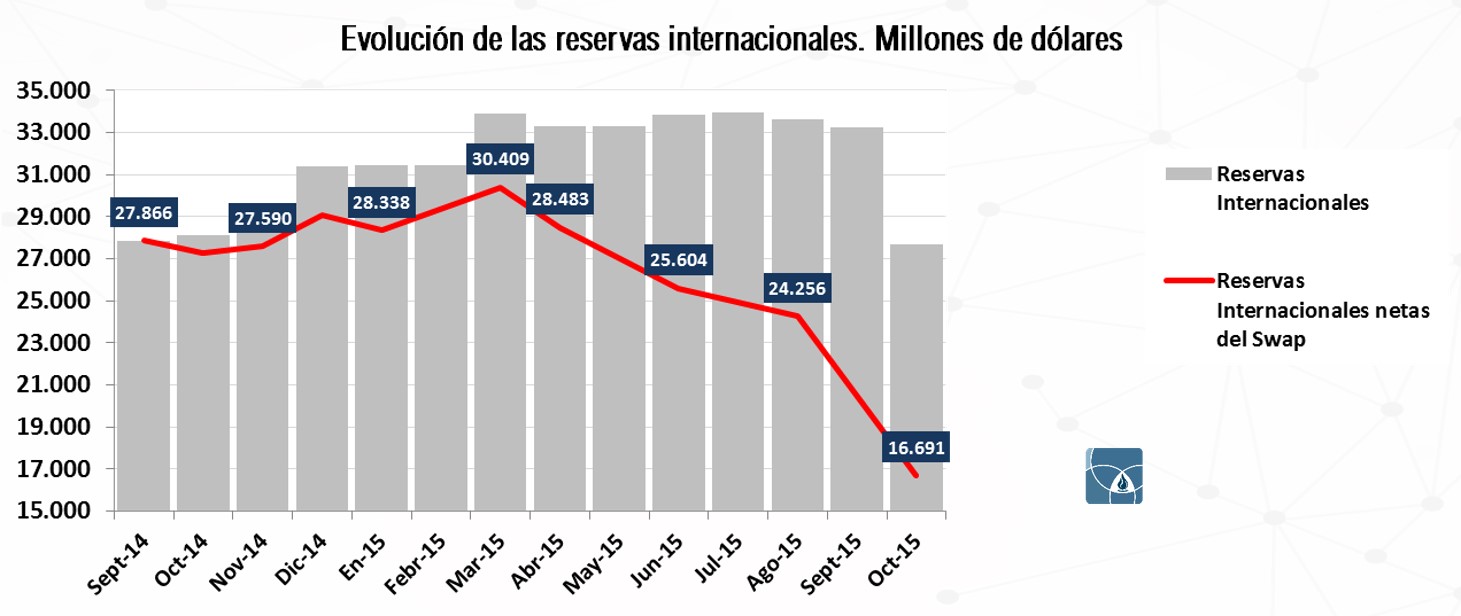
A relief lasting a few months
In summary, so far we have seen that each package of measures aimed at stopping the outflow of dollars from the economy has only had a positive effect in the months following its implementation, but without being able to reverse the long-term trend.
Of the three analyzed, the exchange controls represented a restriction on quantity, the devaluation and easing of restrictions a relaxation of price-based restrictions, and the swap a relaxation of restrictions. The latter appears to have worked best in the short term.
In other words, the underlying problem persists throughout the entire series . However, we have not yet ventured to analyze its cause. The current government's solution, by lifting capital controls and unifying the exchange market, aims to restrict the market through price, thus creating incentives to relax those restrictions.
However, as with previous measures, the consequences won't be seen for approximately six months. This results in three general opinions—let's say, generic ones—about what the consequences of this measure will be.
The three positions: devaluation, appreciation, or confidence
On one hand, there are those who think that, given the large monetary emission, repressed inflation and the high exchange rate gap, an immediate unification and liberalization of the exchange market will bring the price of the dollar in the single and free market to the previous level in the parallel market in the medium term.
They argue that the sharp devaluation of the peso relative to its previous official exchange rate will increase inflation. This will cause a significant drop in real wages and trigger a struggle over income distribution.
On the other hand, there are those who believe that unification will produce a flood of foreign capital leading to an appreciation of the peso. This would result in a loss of competitiveness for export-oriented and import-substitution industries. According to this view, the undesirable effect could be eliminated by removing all taxes that affect competitiveness and discourage efficient investment.
Finally, the last position argues that unifying and liberalizing the exchange rate will not trigger the much-feared dollar-price-wage spiral. This will be the case as long as a consistent economic plan is presented that generates confidence among economic actors and allows for an increase in the Central Bank's reserves.
Stocks, novelty and after
What new developments do the new measures bring regarding strictly exchange rate policy? First of all, they seek to abandon the crawling peg system of progressive and increasing devaluations used by the previous administration.
Note that the official exchange rate at the beginning of the series is over 300% higher at the end. In other words, a gradualist policy has been replaced by a shock policy (which is not captured by the series).
But perhaps the biggest change, which is also the biggest challenge for this government's exchange rate strategy, is replacing the current monetary anchor —the exchange rate—with an inflation-targeting program. What does this mean? When entering into contracts, market participants seek information about their current and future activity.
In an inflationary environment, where prices are expected to rise gradually (although the extent is unknown), signing contracts adds an extra layer of uncertainty. To deal with this, local players use the exchange rate as a reference.
Thus, in the event of a devaluation by the government, there is a transfer to prices far above the tradable component of the goods or services exchanged in the economy.
Without going any further, this was exactly what happened in the devaluation of January 2014. After the measure, the interannual growth rate of the Cenda-Congreso CPI stood at an average rate of 38,56% annually.
Meanwhile, once expectations regarding these types of policies dissipated, during 2015 the year-on-year growth levels of prices returned to around 28,63% annually.
Inflation targets and a credible price index
How can the monetary anchor be replaced to break the pass-through mechanism to prices? The current administration's proposal is to create a monetary program that indicates to the market the inflation targets that the Central Bank is committed to achieving.
In addition to the inherent complexity of honoring these types of commitments, a key component for shaping expectations is missing from the equation: a credible price index that the Central Bank of Argentina (BCRA) reports on.
Thus, until the economy has this tool, most news impacting the monetary front will likely revolve around negotiations with various sectors and agents, a way to buy time until a credible price index can be presented. The final results will be available in six months.
Open access, for use and citation
The report is available freely and without charge, under a Creative Commons license (CC BY-NC-SA 4.0):
- 📄 Full report (PDF): Download the report
- 🗄️ UNR Hypermedia Repository (RepHip): https://hdl.handle.net/2133/17512
- 📚 More reports from the Observatory: Index of Reports
Informe Mensual de Política Monetaria | Julio 2015. Informes del Observatorio UNR N.º 18 — Serie Informes de Coyuntura N.º 9, diciembre de 2015. ISSN 2683-9067 / 2683-9075. Autor: Germán A. Tessmer.