

Cómo evolucionaron la base monetaria, las letras del BCRA, los préstamos al sector privado y las reservas, y qué marcó la política monetaria en febrero de 2015. Informe de abril de 2015.
En esta oportunidad, presentamos nuestro primer informe de coyuntura de carácter mensual. La disponibilidad de datos confiables nos permite abordar con esta periodicidad el desempeño de la monetary politics.
Es decir, la información disponible parece indicar que la política fiscal arrastra las acciones ejercidas por parte de la máxima autoridad monetaria.
Así, uno de los puntos que está configurándose como un problema para este año es el margen de emisión de títulos públicos —especialmente las LEBAC— que le queda disponible a la actual conducción del BCRA, in order to be able to resort to open market policies in order to counteract inflationary pressures, which also appear on other fronts.
Lo más destacado de febrero de 2015
In summary, the points that stand out for the month of in February are as shown below:
- La monetary base The monetary base fell by 0,4% compared to the previous month. However, it accelerated its growth in year-on-year terms, presenting a total increase of 29,5%. It is worth clarifying that the increase in the monetary base is much lower than the private inflation rates, which serves as evidence to highlight that a force is currently being exercised contractionary monetary policy.
- Main monetary aggregates grew in line with the monetary base. In January 2015, the aggregate M2, which includes the circulating currency and the current and short-term deposits of the public, grew by 21,6% year-on-year; while the aggregate M3 The increase was 26,4%. The largest increase was seen in public sector fixed-term deposits. Seen in a disaggregated manner, savings deposits grew by 34,0%, current account deposits by 33,3% and fixed-term deposits by 29,3%.
Préstamos, tasas, letras y reservas
- The lower demand and the high supply of BCRA bills lead to a strong reduction in the loans to the private sector, which barely expanded by 17,5% year-on-year in nominal terms. According to what we have been able to consult with different sources that carry out their work in the banking or capital markets field, the strongest hypothesis that is supported to explain this behavior is that, given the electoral scenario looming, both banks and borrowers are taking a “wait and see” attitude.
- tasas de interés stabilized after the increase they showed at the beginning of 2014. The rate paid by the LEBAC shows the highest growth, even ranking above that of single-signature documents. As mentioned in the introduction, it is in the monitoring of LEBAC rates where part of the margin that the BCRA has to exercise a monetary policy that helps slow down the inflation rate is at stake.
- The expansion of monetary base It is explained almost exclusively by the public sector financing. In parallel, the BCRA continues to carry out a contractionary monetary policy through open market operations. As a result of this policy, the stock of bills issued by the BCRA currently stands at $324.828 million, double that of February 2014.
- international reserves They stopped their downward trend thanks to the use of swap with China.
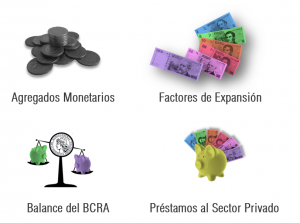
Las cuatro secciones del informe completo.Las cuatro secciones del informe
The report, which we have made available for download, provides a detailed analysis of each of these points. The presentation is structured into four sections, identifiable by the icons shown on the left.
- Evolution of monetary aggregates, where the emphasis is on observing the evolution of the monetary base.
- Expansion factors that guide the monetary base, and it is also where the influence of fiscal policy on the performance of the BCRA is reflected.
- BCRA balance sheet, and it is there where the future possibilities of maintaining –or not- the same type of conduct by the authorities can be observed.
- Loans to the private sector, se analiza la influencia del resultado conjunto en materia de crédito doméstico.
Open access, for use and citation
The report is available freely and without charge, under a Creative Commons license (CC BY-NC-SA 4.0):
- 📄 Full report (PDF): Download the report
- 🗄️ UNR Hypermedia Repository (RepHip): https://hdl.handle.net/2133/17506
- 📚 More reports from the Observatory: Index of Reports
Informe de Política Monetaria | Febrero 2015. Informes del Observatorio UNR N.º 4 — Serie Informes de Coyuntura N.º 2, abril de 2015. ISSN 2683-9067 / 2683-9075. Autores: Germán A. Tessmer y Norberto Martín.