

Why the primary deficit in 2015 started with a 2441% year-on-year increase in the first quarter and how it is sustained by transfers from the Central Bank and the Sustainability Guarantee Fund. September 2015 report.
If we had to choose one phrase from our report, it would definitely be this: “The primary deficit for the first quarter shows a year-on-year increase of 2441%.” Obviously, by the time this publication is released, this observation is already old news.
Market participants have already factored this in, and the primary deficit accumulated in April exceeds the total for 2014. Given this, the contribution of our report is to provide an analysis of the consolidated national budget data. While this analysis is based on current economic data, it allows for a comprehensive view of how this result was reached. To this end, it examines the inflow and outflow of resources during the first three months of the year.
Primary result and genuine primary result
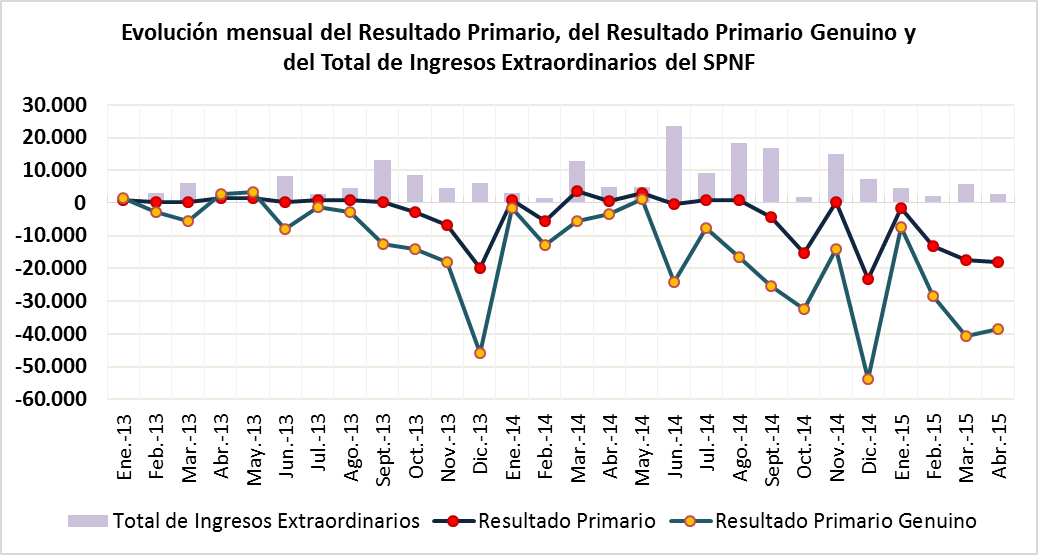
Let's begin with the evolution of the Primary Result . The concept reflects a basic accounting issue: the difference between income and expenses of the non-financial public sector. It does not take into account interest payments on debt, and this last point is precisely what makes it a primary result.
There were some exceptions, such as the one recorded in December 2013, which resulted in a deficit of $19.897,7 million. But throughout 2013 and for much of 2014, the graph shows an effort by the SPNF (Non-Financial Public Sector) to maintain a balanced budget. That effort began to falter in August of last year.
However, this is not what happens when looking at the Genuine Primary Result . This result is obtained by subtracting extraordinary income from the previous formula. Among these, the most notable are transfers from the Central Bank of Argentina (BCRA) and those from the Sustainability Guarantee Fund (FGS) managed by ANSES (National Social Security Administration). As with everything in economics, the use of these mechanisms has its drawbacks.
Central Bank transfers and monetary issuance
In the case of profit transfers by the monetary authority , the problem is that they generate—by definition—more money printing. It's important to understand that this isn't to say that money printing is inherently bad . If that were the case, there would be no possibility of implementing an active monetary policy.
Nor is it being claimed that higher levels of money printing necessarily lead to higher levels of inflation (in and of themselves ). The minimum starting point for a discussion is this: there is sufficient empirical evidence to assert that there is a high correlation between money printing and inflation.
If we add to the above that the growth projections for our economy show a null result, there is room to conjecture that this correlation partially becomes causality.
The profits of the FGS and social security
On the other hand, using the FGS's profits carries the risk of underfunding the social security system. To illustrate this point: between February 2014 and 2015, the value of the portfolio held by the FGS increased by 36,77% year-on-year.
However, using the same comparison for accumulated transfers, these grew by 52,73%, approximately 16 percentage points above the portfolio value growth. Likewise, the SSS balance for the first quarter of 2015 shows a negative amount of $10.356 million. This represents an increase of 119,52% compared to the same quarter of the previous year.
In short, whether by monetizing debts or bringing in future funds to pay current bills, the fact is that in the current situation, these mechanisms are what sustain the primary deficit . Indeed, one of the novel aspects of this first quarter is that the Central Bank's profit transfer mechanism has been practically unused. This explains a large part of the gap that appears throughout the year between the two lines in the previous graph.
Financial result and extraordinary income
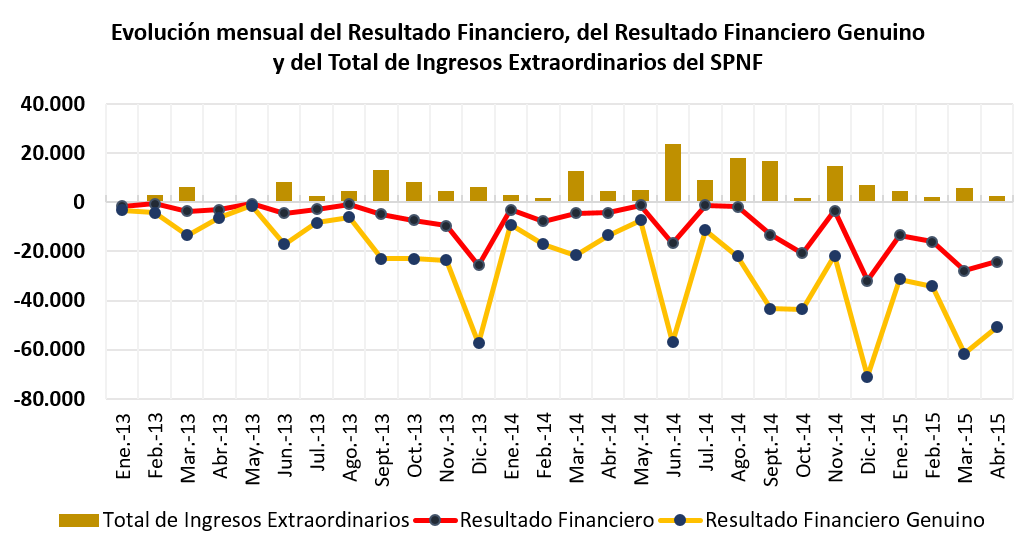
However, the use of extraordinary mechanisms makes more sense when considering the evolution of the Financial Result and the Genuine Financial Result . Both include debt interest payments.
The correlation between Total Extraordinary Income and Genuine Financial Result is much higher than that established between the latter and Genuine Primary Result.
Thus, everything seems to indicate that there is a greater willingness to use resources from the BCRA and the FGS in months where interest payments or debt capital repayments must be made.
As usual, we invite you to further analyze the report by downloading it below.
Open access, for use and citation
The report is available freely and without charge, under a Creative Commons license (CC BY-NC-SA 4.0):
- 📄 Full report (PDF): Download the report
- 🗄️ UNR Hypermedia Repository (RepHip): https://hdl.handle.net/2133/17509
- 📚 More reports from the Observatory: Index of Reports
Informe Trimestral de Cuentas Públicas | I Trimestre de 2015. Informes del Observatorio UNR N.º 10 — Serie Informes de Coyuntura N.º 6, septiembre de 2015. ISSN 2683-9067 / 2683-9075. Autor: Germán A. Tessmer.