

What measures did the 2017 tax and labor reform include, and how did it fit into a context of inflation, fiscal deficit, and growing debt? November 2017 report.
On October 30, 2017, the Executive Branch presented a broad package of reforms covering diverse areas such as the judiciary, taxation, and labor. These reforms have generated a great deal of political analysis. This is due to the immediacy of their presentation, following the ruling party's victory in this year's midterm elections.
The purpose of this note is to step back from that perspective and present an analysis of the measures included in the reform package within the macroeconomic context in which they are presented. In other words, within their context.
This entry is accompanied by a detailed report on the state of the country, in monetary and fiscal aspects.
The report addresses the role of the Central Bank in combating inflation, its influence on exchange rate policy, existing tensions with the Treasury, and the problem of fiscal and trade deficits. Finally, it examines the need to buy time by issuing debt and the vulnerabilities this entails.
The measures (a summary)
Taxes for companies:
- The corporate income tax rate will be lowered, with the aim of encouraging companies to reinvest their profits.
- For those companies that reinvest their profits, there will be an early refund of VAT. This is intended to reduce the financial cost of investment projects.
- Employer contributions will also be modified, with the aim of reducing informal employment.
Other taxes:
• The check tax may be used as payment on account of profits.
• It was proposed to reduce, in each province, the taxes corresponding to gross income and stamps.
• As for the self-employed, it is proposed to double the amount of special deduction in Income Tax, going from $50.000 to $100.000.
• New tax scheme for financial income, which will be taxed in certain sections.
Consumer Taxes:
- Cell phones, televisions, monitors and other similar products go from paying 17% of internal taxes to 0%
- Mid-range cars and motorcycles will have their taxes reduced from 10% to 0.
- Cigarettes will have their tax rate reduced by 5 percentage points, reaching 70%
- The VAT tax base is expanded to include digital services.
- Soft drinks in general and other non-alcoholic beverages gradually increase from 4 to 8% for those with added sugar to 17%. It should be noted that light or sugar-free beverages maintain 0%.
Principales medidas de reforma laboral
The labor reform bill entails significant changes to the employment contract system. The main ones are detailed below:
- The employer is authorized to introduce all changes relating to the form and modality of the provision of work.
- Part-time contract.
- Changes in worker's licenses
- Collective bargaining agreements may establish compensatory systems of time credits known as “Hour Banks”.
- Modification to the calculation of Compensation.
What effects are expected from the measures
As can be seen, most broad-scope tax measures tend to reduce the pressure or alleviate problems of mismatch with respect to payment terms.
On the other hand, rates are created or increased for specific goods, whether they are considered luxury goods or consumer goods that can be considered related to health expenditure of the population (such as the case of sugary drinks).
From the tax authorities' perspective, the direct and immediate effect is estimated to be a decrease in revenue. However, there would be some relief in out-of-pocket spending for consumers, due to lower prices for the affected goods. This price reduction may not be fully absorbed by households. This is explained by the generally imperfectly competitive market structure in which the Argentine economy operates.
The indirect effect is expected to be greater economic dynamism. This is attributed to the profit margins available to businesses as a result of lower taxes. Added to this are expectations of lower costs in that area.
All of which results in the use of the debt mechanism to tolerate the cost of the readjustment that the measures imply if they are approved.
The fiscal dilemma: lower taxes, more activity
In terms of the general strategies available to the government to alleviate the problem of the fiscal deficit , the bet from a tax point of view consists of the following dilemma: decrease tax pressure (and, therefore, tax revenues) to increase the activity of companies (to increase collection).
Companies operate in imperfect market structures. Therefore, it is likely that a large portion of the profit margin remaining after the tax cut will be absorbed by them.
In that sense, the policy implementation question is whether that surplus will be reinvested to generate more economic activity. And more importantly, whether the sacrifice in tax revenue will ultimately be compensated.
Furthermore, it is worth noting that the proposals presented do not include any additional spending reduction measures beyond those already being implemented in terms of subsidy cuts.
One of the limitations in this regard is that it is estimated that approximately 60% of expenditures are indexed. This creates rigidities that ultimately focus the bulk of the fiscal effort on areas that do not have this characteristic. Again, subsidies.
labor reform
Finally, the most delicate point concerns labor reform . In general, it is observed that after the past decade of high commodity prices , Latin American economies are converging toward reforms of their labor markets. These reforms tend to achieve different conditions of formality and mobility.
This includes expanding the types of contracts that can be contracted, adjusting them to the changing requirements of the productive sector, while seeking to guarantee the security of workers in terms of labour formality.
On the other hand, there is a trend toward promoting adaptations to more specialized profiles. This occurs within the context of a technological change process that aims to eliminate certain existing jobs. This same process tends to replace them with the emergence of new positions and tasks in the labor market.
Furthermore, there is a trend towards analyzing and reorganizing issues related to the pension system , mainly by postponing and equalizing the retirement age between men and women.
At this point, the country and the region are not immune to a global context where concerns abound about how to sustain and finance pension systems in the medium and long term.
The downside of this process, which generates skepticism primarily within the labor sector, is the potential loss of workers' rights. Another concern is the lack of a proper institutional framework to enforce the changes. This is exacerbated by the existing asymmetry in bargaining power between companies and their employees.
However, these types of questions are in contrast to the fact that around 30% of workers work in the informal economy, where union representation has no influence.
The context
How can the consolidated state of the Argentine economy be reconciled with the package of reform measures being promoted by the Executive Branch?
The Central Bank has designed an anti-inflation plan with four pillars. One of them is to end fiscal dominance, which is the one that poses the greatest challenges for the highest monetary authority.
For its part, the Ministry of Finance has promoted a plan with targets for reducing the fiscal deficit. This plan is consistent in its conception with the solution to the aforementioned problem.
Thus, the problem between both policies lies mainly in their coordination, especially with regard to the implementation times of the objectives of each plan.
In this sense, while the Central Bank seeks to combat the inflationary process, the Treasury seeks to increase - or at least maintain - the level of economic activity.
The analysis shows that the process of reducing the public deficit is currently proceeding at a slower pace than required by the monetary authority.
Since both types of policies influence each other, in order to gain time in the simultaneous implementation of both plans, the Argentine economy has entered a process of taking on debt, both internal and in dollars.
However, like virtually every measure in the economy, this strategy ends up conditioning the previous ones, by modifying the path of increase in the consolidated deficit.
The Central Bank: debt, reserves and interest rates
Thus, with regard to the Central Bank of Argentina (BCRA), since the new government took power, the institution's liabilities have doubled. There have been significant increases in the monetary base and in the level of debt held through LEBACs (Central Bank Bills ). These latter bills represent the largest component: 36,15% of the BCRA's liabilities at the end of June 2017.
On the other hand, within the entity's assets, international reserves also doubled, driven mainly by a higher level of debt, the liquidation of exports for the year, and the result of the money laundering process.
Under this strategy, the Central Bank seeks to control core inflation . To that end, it offers a LEBAC rate that has remained – practically – above 25% annually throughout 2017. This gradually reduces the amount of pesos in circulation and extends the potential impact on the general price level by staggering maturities and subsequent renewals.
Consequently, the cost of this strategy is increased interest payments, which in 2017 became a positive real payment. Thus, the problem facing the monetary authority remains that of fiscal dominance.
In this regard, it is worth noting that both temporary advances to the Treasury and the holding of non-transferable bills have decreased drastically in favor of the Central Bank's anti-inflation plan.
However, the relatively high level of projected global deficit—for the time being—threatens this objective. Following the subsidy cuts of 2016, inflation is declining, although not at the projected rate, particularly with regard to core inflation.
Inflation above the target
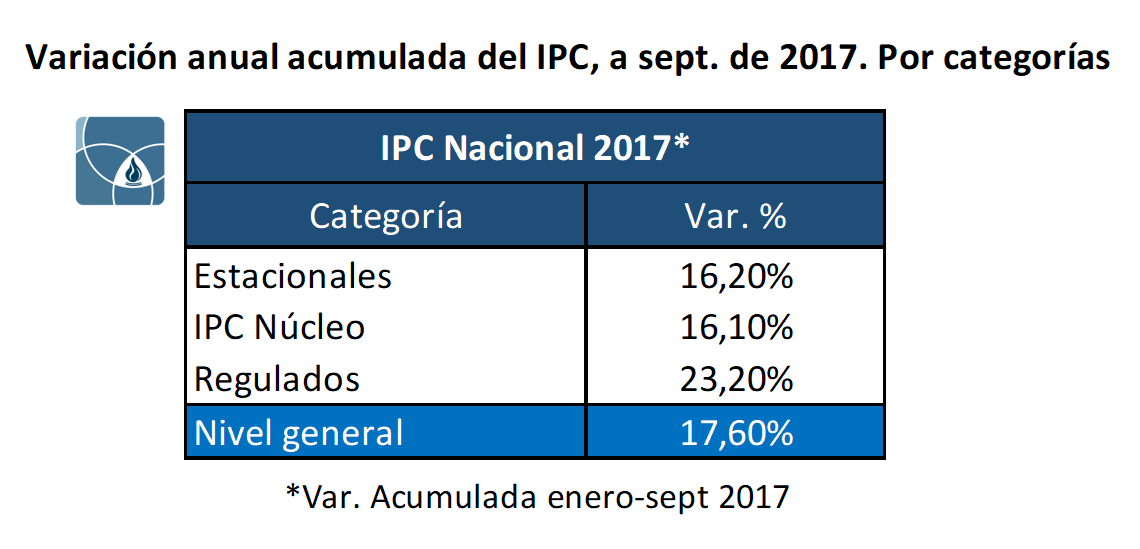
Thus, in September, inflation as recorded by INDEC was 1,9%. This level exceeded the 17% target set as the maximum for 2017 by the Central Bank of Argentina (BCRA) in its inflation targeting plan.
As a result, the overall cumulative level for the period January-September 2017 is 17,6%, although annual estimates remain in the range of 20% to 23%.
The following table shows the cumulative annual evolution of the different categories of goods this year. The table shows that, as a result of the tariff adjustment, regulated goods and services continue to show a greater increase compared to other goods, similar to what occurred in the first half of the year.
The Treasury: revenue and spending
From the Treasury 's perspective , the dilemma lies in how long to maintain the current deficit level and, consequently, how to finance it. In other words, the general strategies available are: increase revenue or decrease spending.
As for the first option, 2017 is showing a slight improvement in tax collection compared to 2016, and this is precisely where the reform package has a strong impact.
However, the decline in economic activity has affected the main sources of tax revenue (VAT and income tax). Meanwhile, the drop in revenue from tradable goods was even more pronounced in the first half of 2017. This was also due to the changes in the withholding tax system.
Meanwhile, the social security system faces increasing challenges, which are making it increasingly deficit-ridden. The profits from the Sustainability Guarantee Fund (FGS) have been allocated not to financing current expenditures, but—primarily—to provincial housing programs.
Regarding spending control, whether capital or current, the information presented shows marked stability in real terms. The exception is two items that change abruptly in composition. Social security spending shows an 89,01% increase between the second quarter of 2015 and the second quarter of 2017. Subsidies, on the other hand, show a 41,42% decrease for the same period.
Deficit, debt and exchange rate
While a reduction in the primary deficit is projected, this is partly due to increased borrowing. This results in a financial deficit (including interest payments) that is decreasing more slowly and has much more rigid components in its structure. In 2016, interest payments represented 33% of the financial deficit, but by 2019 they are projected to represent 63%.
In this way, the public sector's deficit is being financed with higher levels of debt , leaving the country exposed to sharp corrections in the international interest rate.
Furthermore, the increase in debt puts greater pressure on the supply of currency in the foreign exchange market. This impacts the dollar's exchange rate, creating the risk of currency overvaluation.
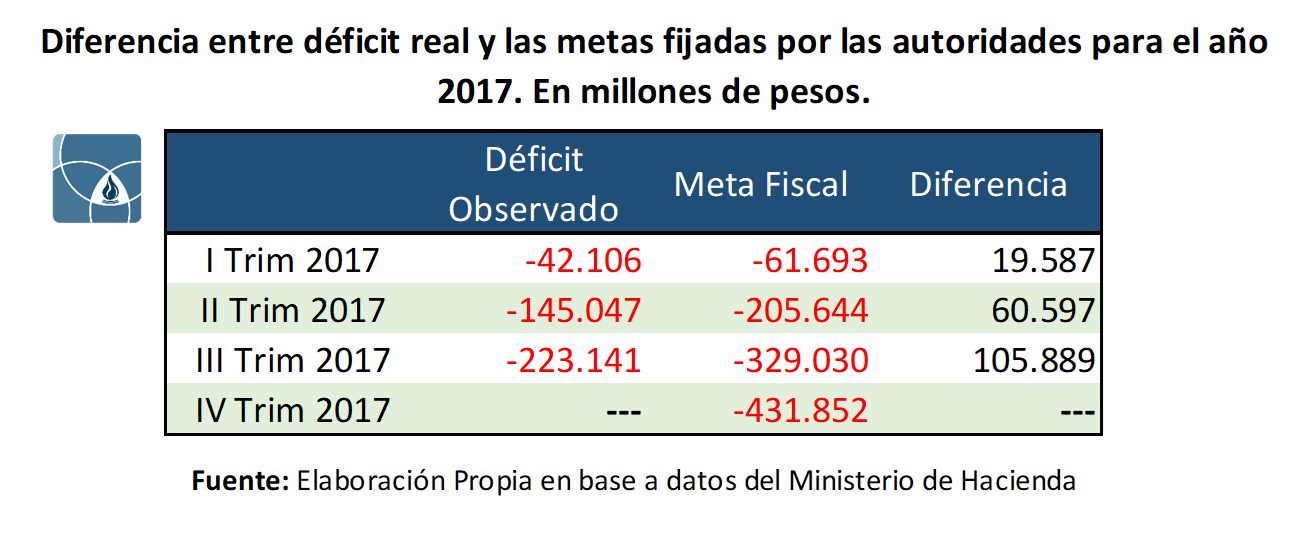
However, as can be seen in the table above, the goals set by the national government have been comfortably met up to the third quarter of this year.
In other words, gradual fiscal policy and a more shock-oriented monetary policy tend to lead to real appreciation of the peso . Consequently, they limit the possibilities for economic expansion through international trade.
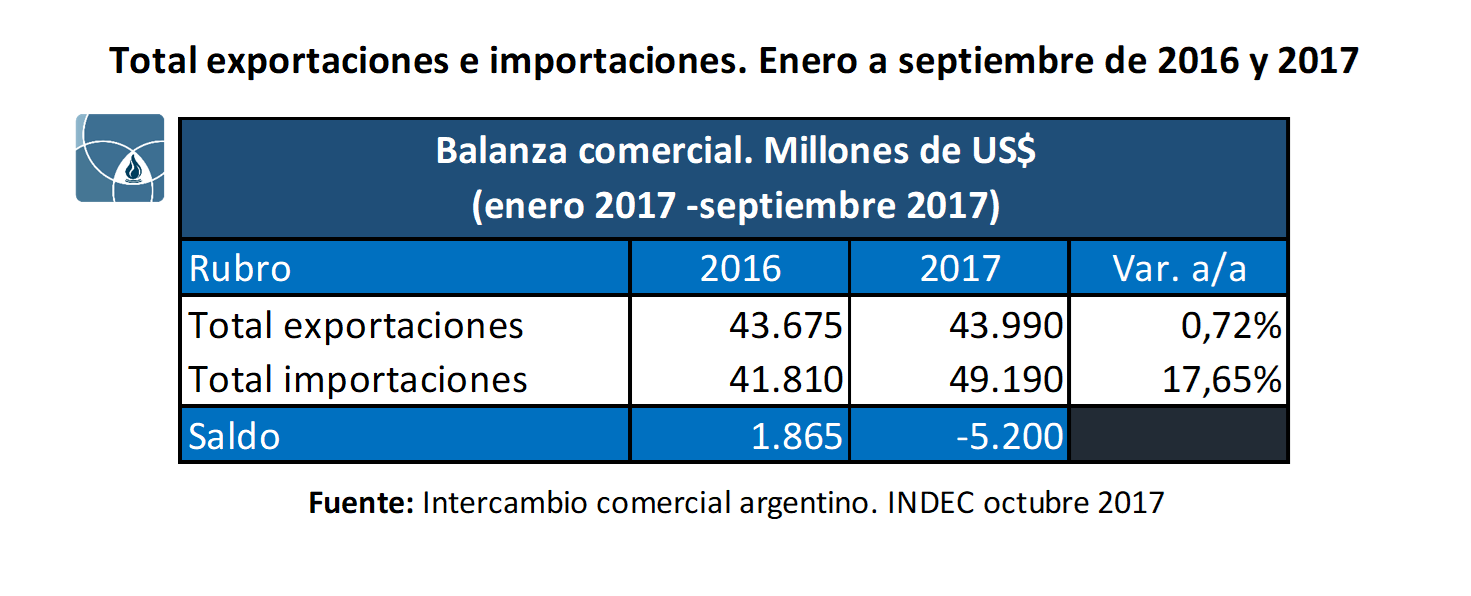
On the other hand, if the economy were to grow due to other factors, given the current production structure, it would inevitably lead to an increase in imports, putting greater pressure on the trade balance.
Botton line
Each of the points raised in this note is extensively justified within the report "Buying Time: Current Situation and Dilemmas of the Argentine Economy," which we have made available to you. This report offers a detailed analysis of the performance of the Central Bank of Argentina (BCRA) and the national public sector, in fiscal terms.
For now, nothing is certain. These measures are expected to be the focus of debate in the National Congress. However, their fiscal impact remains unclear, given the dilemma of promoting greater economic activity at the expense of lower tax revenue.
Open access, for use and citation
The report is available freely and without charge, under a Creative Commons license (CC BY-NC-SA 4.0):
- 📄 Full report (PDF): Download the report
- 🗄️ UNR Hypermedia Repository (RepHip): https://hdl.handle.net/2133/17516
- 📚 More reports from the Observatory: Index of Reports
Las reformas de nuestro tiempo: estado de situación general de la economía argentina. Informes del Observatorio UNR N.º 40 — Serie Informes de Coyuntura N.º 13, noviembre de 2017. ISSN 2683-9067 / 2683-9075. Autores: Germán A. Tessmer, Luciano A. Jara Musuruana y Patricio H. Almeida Gentile.