

What room for maneuver did the Argentine economy have before the 2015 runoff election: comparison with the region, employment, deficit, money supply, inflation, and the dollar. November 2015 report.
No one could jump, no matter how small, without a point of support. If such a thing were possible, it would defy all laws of physics. The reason is simple: you can't jump into a void.
Next Sunday, November 22nd, our country will participate for the first time in history in a presidential runoff election . The procedure itself is unchanged, except that this time there are two options, and these are final.
That is, they are the best that our political system knew how to process. Each has its benefit, and every benefit entails risk. So, when deciding the vote, what is our support point?
The candidates' proposals and biographies
Of the more general options, a first one would be to evaluate the candidates' proposals . After the presidential debate, it's still not entirely clear what each team would do about the future of the economy.
Generalities abound, without much concrete data. What is definitely clear is what candidate A conjectures about what candidate B would do if the latter were to win (and vice versa).
In our opinion, this does not seem to be a good foothold, for the simple reason that every conjecture is mediated by the interest in the other candidate losing.
Another option is to extrapolate from each candidate's biography , including the achievements and successes of their past administrations, the people who accompanied them, their statements and contradictions, etc. In other words, to perform the somewhat detective-like exercise of inferring future behavior based on past observations.
This article does not aim to make that task easy, but we would like to point out some issues that are not at all obvious. Under this framework, the following come to mind:
– How to separate the relevant from the irrelevant? Or in lunfardo, how to separate the chaff from the wheat? Not every anecdote characterizes interpretable behavior, nor does every past achievement prefigure a future achievement.
– What happens with the learning curve? Regardless of the bias that each citizen has for one candidate or another, both are presidential candidates. They are the best that our current political system can give. They are what society built. Therefore, it is not a risky hypothesis to assume that both took note of their past mistakes and have no intention of repeating them. It is insisted, both.
The current economy as a point of support
In this article we reiterate another point of support, which is to observe the current state of the economy , which necessarily limits the scope of action of the future president.
To use a more colloquial term, having a current snapshot of the economy (as well as the configuration of the political system, or the citizenry itself) defines the playing field. It indicates the limits within which the game can be played, but not how it will be played.
In this sense, this article offers a partial point of reference: it doesn't offer an explanation of what will happen. But it does offer alternatives for filtering out what definitely cannot be achieved.
Argentina in context
It doesn't seem to make much sense to compare our country with the standard of living of European countries, much less with the US or Canada. These comparisons can serve to establish a sense of improvement in some aspect that is supposed to be better, but not to characterize the performance of our economy.
Our situation is simply different. In the table below, we have selected variables and Latin American countries. These countries—like ours—have benefited from the rise in commodity prices over the last decade.
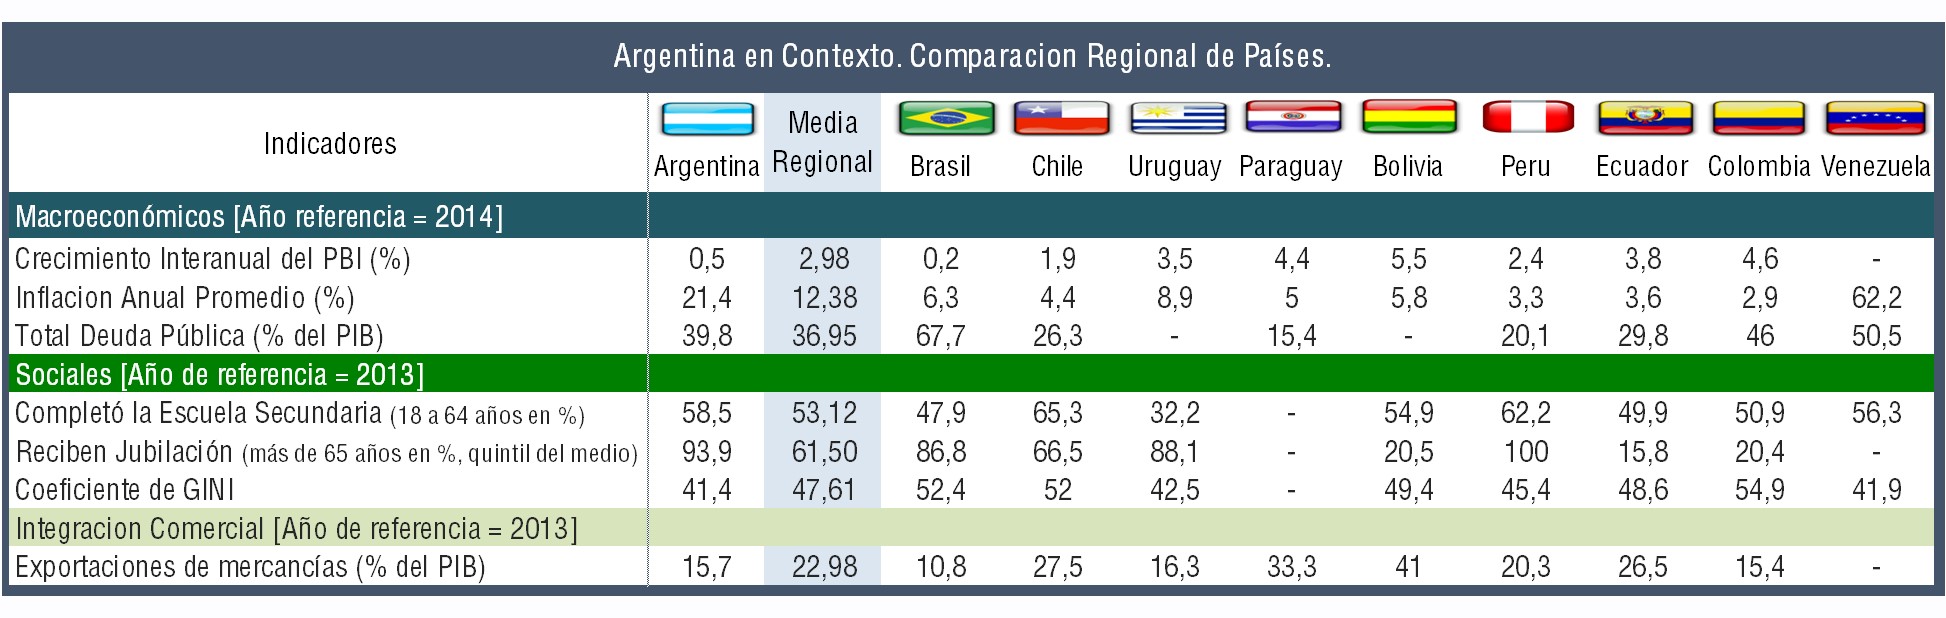
In very general terms, the table shows that with respect to the macroeconomic profile and global integration, our country is below the regional average in all the selected indicators. However, when analyzing the social landscape, the opposite is true: Argentina is above average.
All of which seems to tell the following story : the social performance is good, even slightly above average. But it would appear that there aren't enough resources to sustain it at that level. In any case, this is one of the big questions any voter will have to answer.
Inflation and growth in the region
One point to consider is that inflation is not a regional problem. To date, Venezuela has the highest inflation rate in the world, while Argentina ranks third globally.
For example, the average annual inflation rate in Uruguay in 2014 was 8,9%, compared to 21,4% recorded in our country.
A second issue concerns the region's growth. It is true that Latin America is experiencing a general decline in the prices of its export products and has suffered the effects of the international crisis.
Following the default, Argentina was cut off from the flow of financial capital. Therefore, it did not feel the impact directly, but rather when its main trading partners were affected.
For example, Brazil. In other words, the effects of the crisis did not hit the capital account directly, but indirectly the trade balance. Even so, the region has grown at an average level of approximately 3% annually.
The social landscape: education, pensions and equality
To balance the above, let's look at what's happening in the social landscape . It's clear that our country has better results than the regional average.
The percentage of people between 18 and 64 years old who completed secondary school places us as the third country with the highest percentage. The passage of Law 26.206 made secondary education compulsory. This led to the implementation of several programs to enable those who had not yet finished secondary school to do so.
The second indicator refers to the percentage of people of retirement age. The moratorium implemented in our country allowed a large number of people to be incorporated into the pension system without meeting the contribution requirements. A full evaluation of this measure undoubtedly requires a separate and extensive report.
Among the benefits of the measure, a greater number of people have been incorporated into the pension system. It is estimated that these individuals spend virtually all of their pensions on consumption.
On the other hand, social security spending is the highest in the national budget. It represents approximately 30% of it, and the net balance of the social security system is in deficit ten of the twelve months of the year.
Finally, regarding income concentration, it is observed that our country's Gini coefficient is the lowest in the region. This means that, according to this indicator, Argentina has better levels of income equality compared to its regional counterparts.
Having made this comparison, let's now see what is happening within the country.
At the end of 2015, what is an average Argentinian like?
In terms of gender , she is probably female, although she could very easily have been male. She is between 25 and 45 years old, and although she is not the head of her household, she has a job. Perhaps that is one of the reasons why she has some kind of health insurance through a social security program; the other is because she receives it from her family.
It is also likely that most of her life was spent in the area, or even in the town where she was born. In fact, within the family structure of the home, she fulfills the role of daughter.
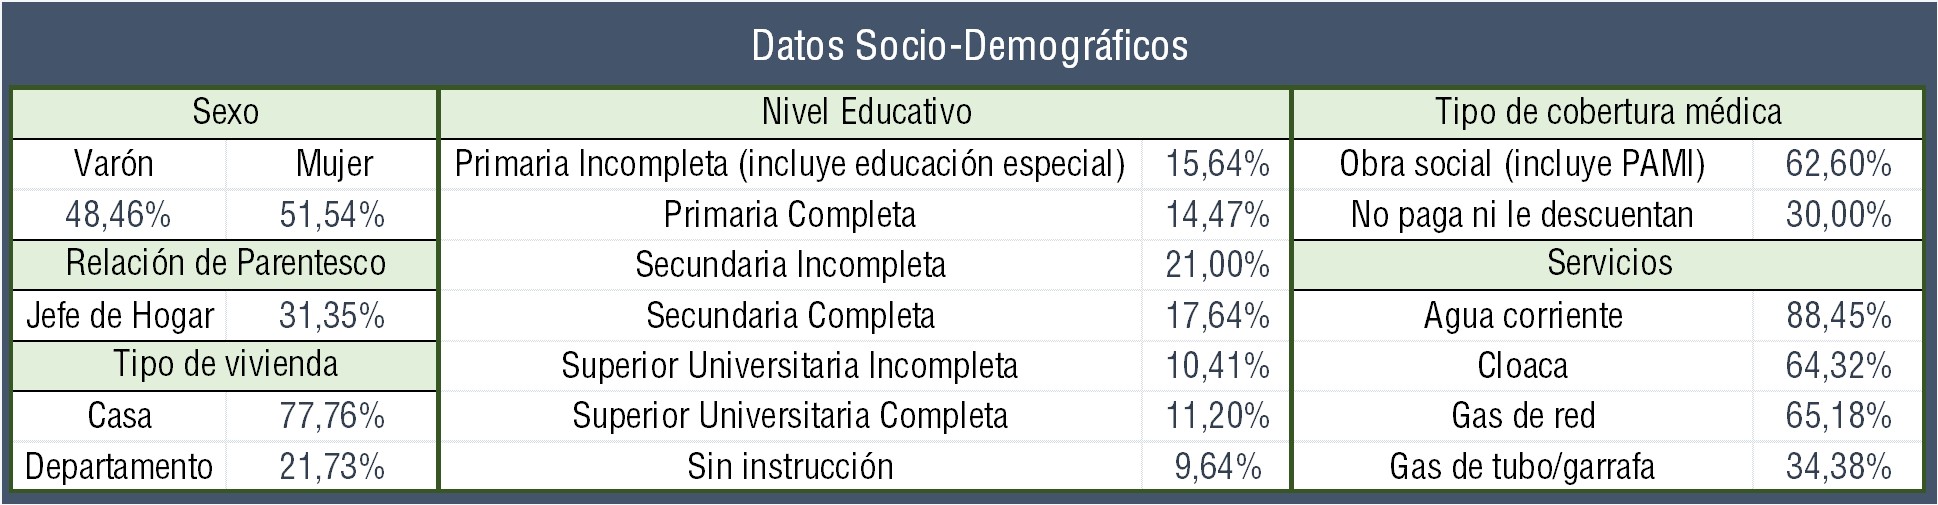
With regard to your quality of life, measured by the type of home and the services available, you probably live in a house that is connected to the running water network, the natural gas network and the of sewers.
Our typical Argentine woman has studied at public institutions, but was unable to complete high school.
The state as a solution and problem
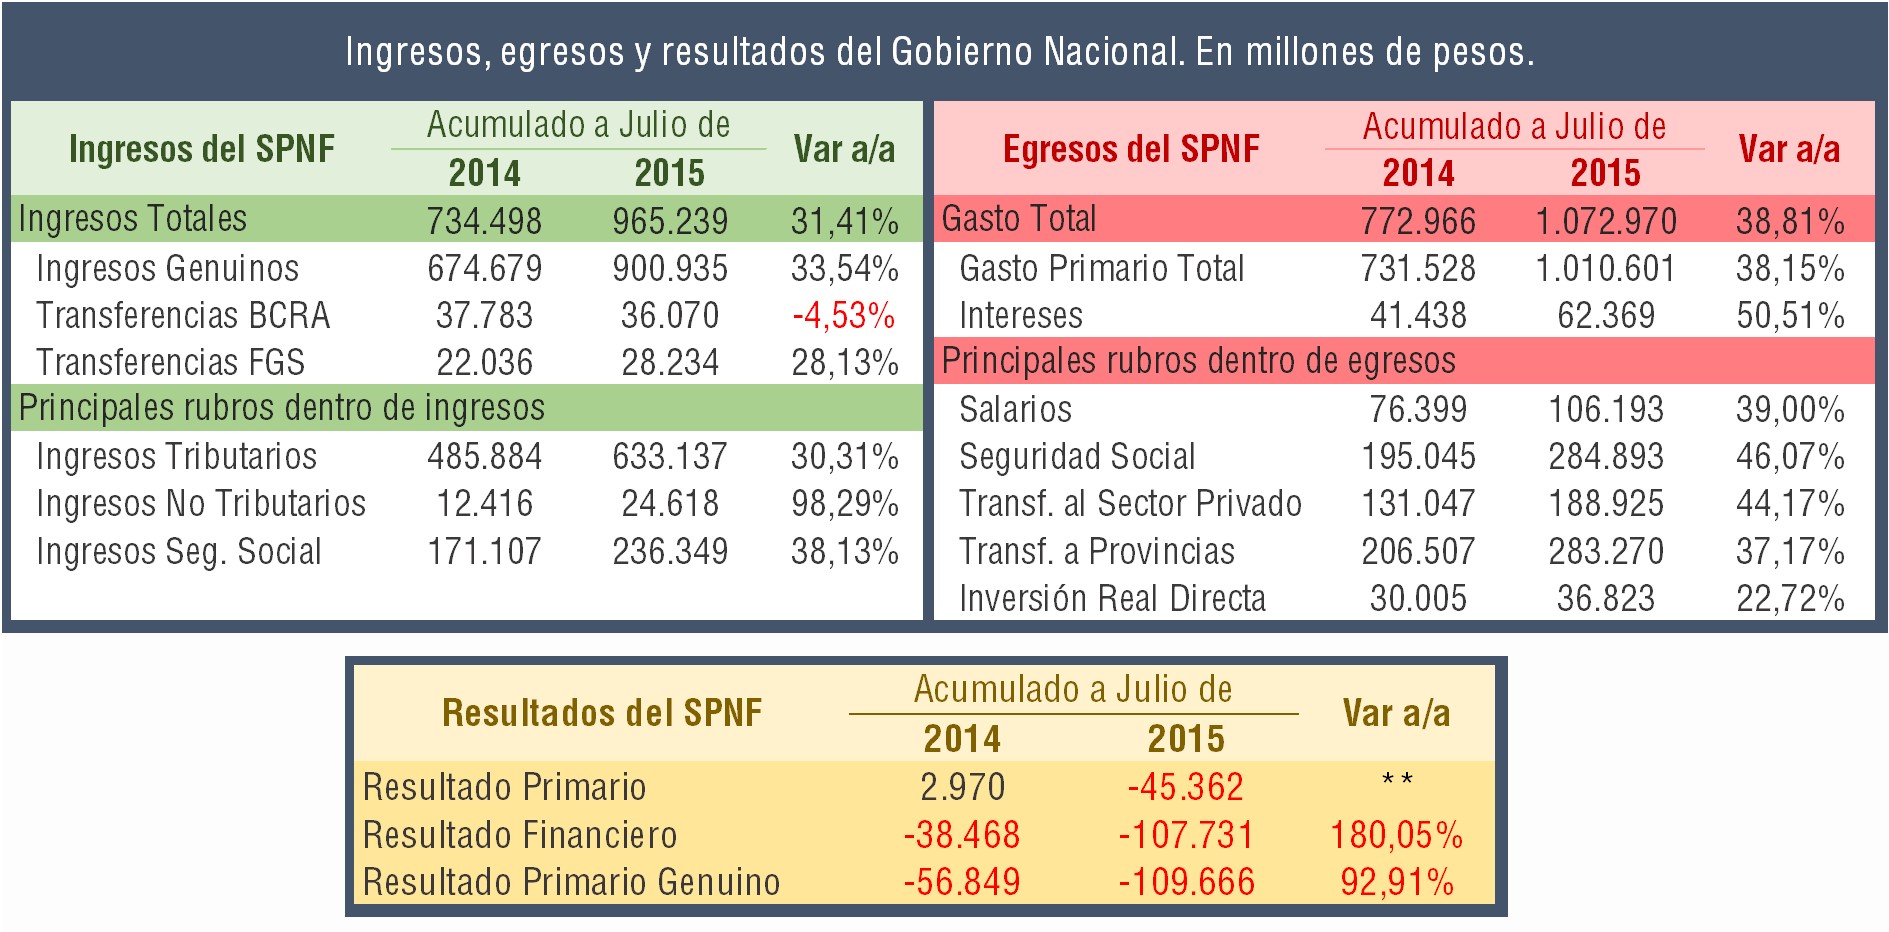
At the end of 2015, it will be the fourth consecutive year in which the result of the non-financial national public sector (NFPS) shows a primary deficit , with the peculiarity that this has been increasing year after year at a rate well above that of inflation.
So much so that the accumulated deficit for the first seven months of the year amounts to $45.362 billion. This figure is 17,64% higher than the total deficit for last year. If we add to this the interest payments on the debt, the following table shows that the financial deficit has increased by 180% between the accumulated figures for July of each year.
In other words, the national government is not only operating beyond its means, but has also been heavily indebted to keep up the pace.
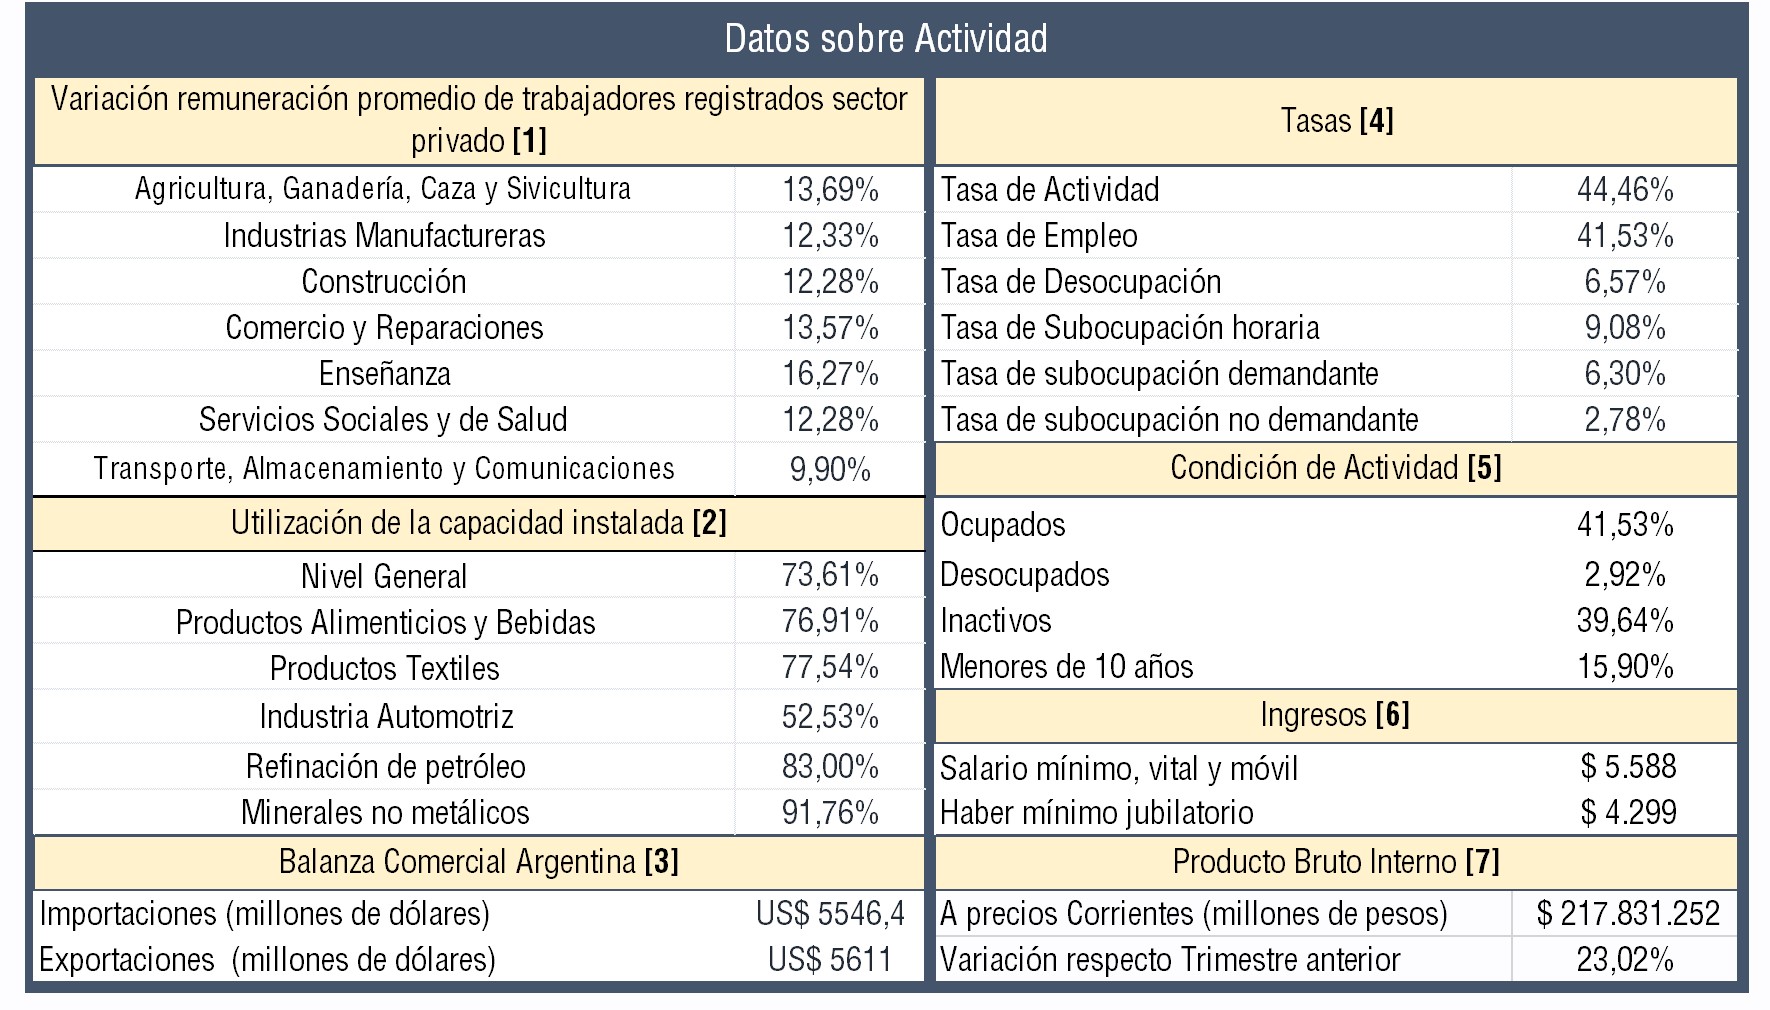
Even so, the current problem is fundamentally one of timing . Why? Because for the domestic market to be sustainable, it needs dollars . Foreign currency that allows the purchase of imported inputs so that productive activity and the domestic market can—at a minimum—maintain an activity level of 44,46%. One way to acquire dollars is through the trade balance.
However, if we look at the table of activity indicators, we can see that as of September of this year, the trade balance shows virtually no surplus, in a context of payment delays for imports already made. This leads us to the most immediate problem: the monetary one.
It's the dollar, it's the peso
In our previous reports, we have characterized monetary policy as dominated by fiscal policy. While government spending expands, the primary balance is partially sustained by transfers from the ANSES Sustainability Guarantee Fund and by transfers from the Central Bank, both to the Treasury.
In fact, if these mechanisms did not exist, the genuine primary result accumulated at the end of July of this year shows that the deficit would amount to $109.666M, with a year-on-year increase of 92,91%.
The problem lies in the fact that by using the various sources of financing by the BCRA in favor of the Treasury, debt is being issued or structured.
The first point indicates that the monetary base is growing, and therefore, there is more money circulating in the economy. So much so that by the end of July of this year, the amount in this category had already reached $520.170 million. This represents a year-on-year growth of 39,95%.
To absorb the oversupply of currency in circulation, the Central Bank of Argentina (BCRA) has been issuing treasury bills at an accelerated pace. It is doing so at an average annual interest rate above 30%. The following table shows that as of July of this year, the stock of treasury bills stands at $355.880 billion. Its year-on-year growth rate is 57,8%.
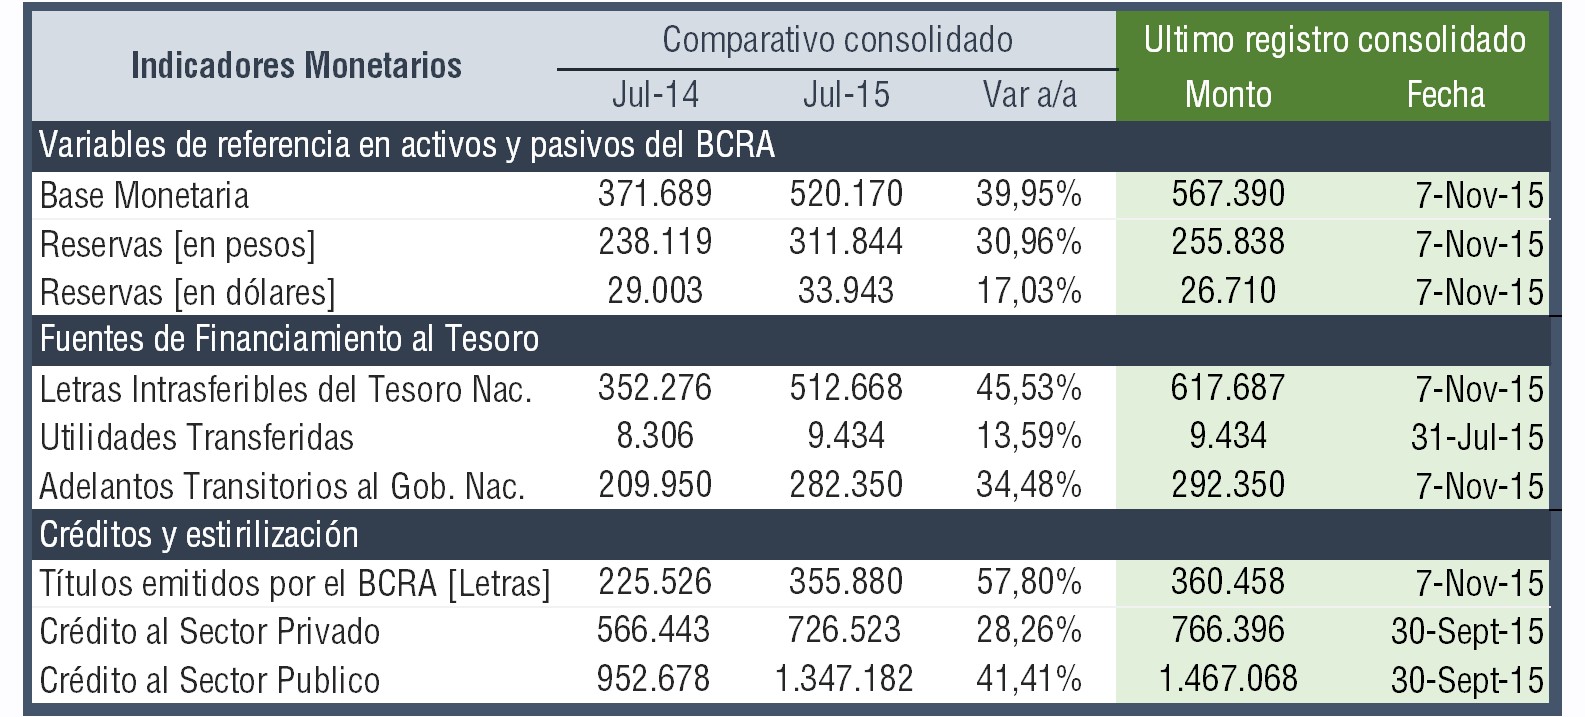
Indicadores monetarios del BCRA en julio de 2014 y 2015 y su último registro disponible.Central Bank reserves
Likewise, outstanding balances that are not absorbed impact the general price level or end up putting pressure on the demand for dollars. This leads to a consequent loss of reserves for the Central Bank. Thus, reserve stock registrado a fines de julio muestra una cifra de US$ 33.943M en el activo del BCRA, con un crecimiento del 17,03% con respecto al mismo mes del año pasado.
However, the latest consolidated data available shows a sharp drop in reserves, resulting from the payment of interest and principal on the BODEN 2015 bond, which was canceled on October 4th of this year. What the table also fails to show is the composition of those reserves. In other words, how many dollars are genuinely owned by the Central Bank.
Inflation, wage negotiations and the real exchange rate
Regarding price adjustments , the following table shows two indices. As of July 2015, INDEC inflation shows a growth of 14,85% compared to the same month of the previous year, while CENDA-CONGRESS inflation shows a significantly higher growth, on the order of 27,15% year-on-year.
Of course, in our country annual parity payments have been implemented in order to counteract the effects of inflation.
The problem with this mechanism is that it generates an inertial increase in prices for the following period, in addition to distorting the relative price system, since the unions in the sector with greater bargaining power are the ones that can gain greater improvements for their members, with certain independence of their productivity. As always in economics, every benefit has its cost.
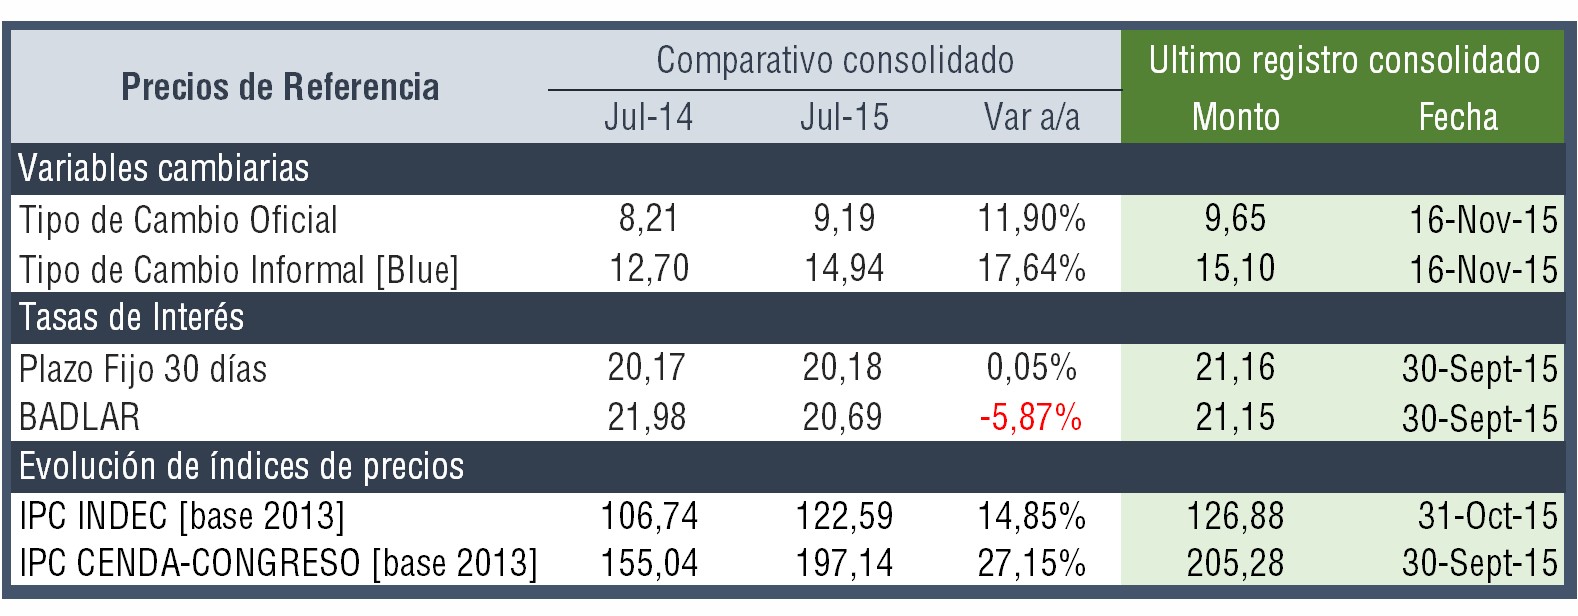
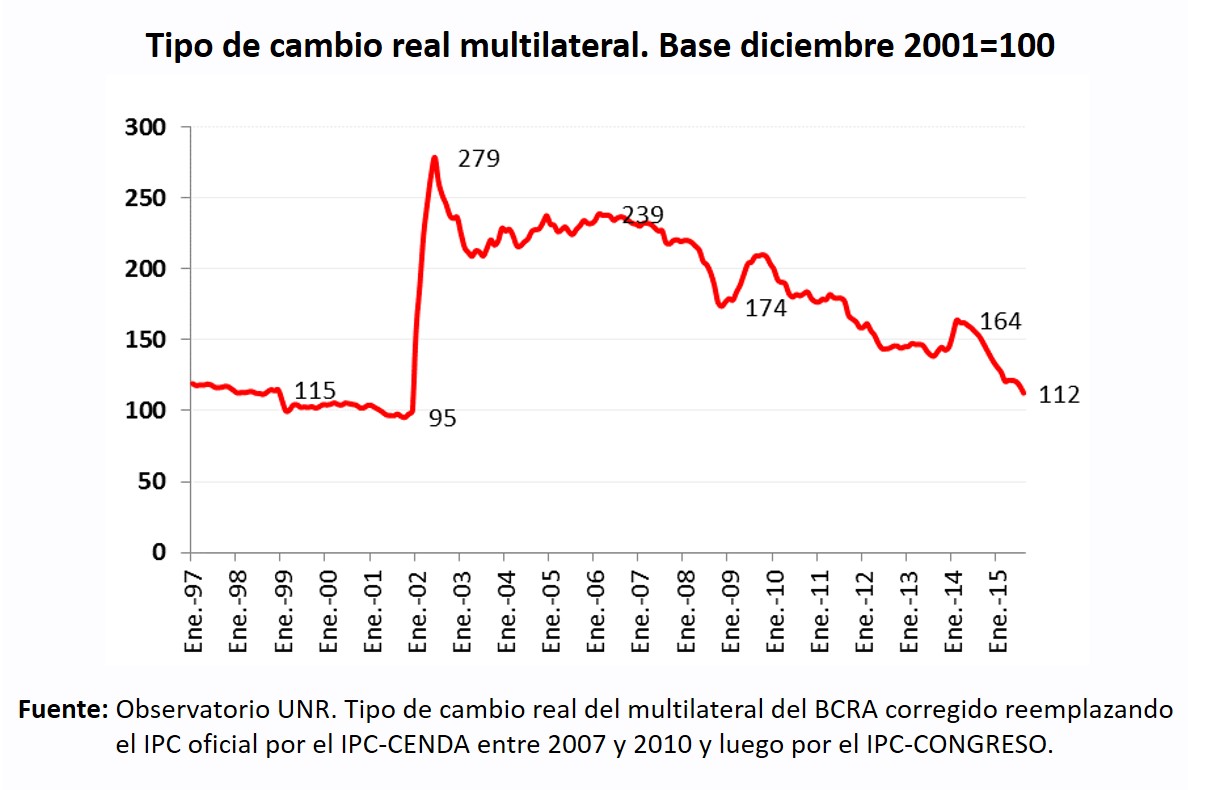
Tipo de cambio, tasas de interés e índices de precios en julio de 2014 y 2015 y su último registro disponible.Finally, the internal price increases, growing at a rate higher than the devaluation rate, ultimately impacted our economy's real exchange rate , causing it to appreciate. What does this mean? It means that the value of goods produced in Argentina, measured in dollars, became significantly more expensive compared to other countries, thus hindering our ability to sell our goods abroad.
In summary, if the current problem is obtaining genuine dollars in order to maintain the level of activity, making our exports more expensive goes in the opposite direction to solving the problem.
The capital account and Griesa's ruling
The entire argument above is missing something: the capital account. That is, the possibility of dollars entering the country through portfolio investment, direct investment, or by taking on debt. The problem is that this option is nullified by Judge Griesa's disastrous ruling against Argentina.
This leads to two main sets of options: either dollars are obtained through financial instruments established bilaterally with other countries (as is the case with the swap with China), or an exit is negotiated with the holdouts in order to be able to re-enter the international credit markets.
Meanwhile, on the domestic front, the presence of currency controls, coupled with the inflationary scenario, is increasing pressure on the Central Bank to sell the dollars it does not yet have and is trying to obtain.
Give me a foothold and a lever big enough, and I will move the world
In recent months, the events of 2001 have been frequently recalled. To conclude this article, we propose a different exercise: to think about 2003, when the characteristics of what was called the model had already been consolidated. What were they?
- High real exchange rate (depreciated)
- Fiscal surplus
- Trade surplus
- External debt relief
- High social spending
Of all those characteristics, only the last one remains to this day. Furthermore, the circumstances in which the solution to the crisis was developed—that is, the context in which that solution was able to work—included the following factors: low installed capacity and high unemployment, conversion of dollar-denominated debts to pesos, a sharp prior devaluation, and high international prices.
The landscape depicted in this article about the current state of the economy clearly shows that none of these factors are present.
Open access, for use and citation
The report is available freely and without charge, under a Creative Commons license (CC BY-NC-SA 4.0):
- 📄 Full report (PDF): Download the report
- 🗄️ UNR Hypermedia Repository (RepHip): https://hdl.handle.net/2133/14515
- 📚 More reports from the Observatory: Index of Reports
Elecciones: La foto de la economía, hoy. Informes del Observatorio UNR N.º 17 — Serie Puente Académico N.º 4, noviembre de 2015. ISSN 2683-9067 / 2683-9091. Autores: Germán A. Tessmer, Luciano A. Jara Musuruana y Norberto Martín.