


In the years following the default at the end of 2001, through two voluntary debt exchanges in 2005 and 2010, the government managed to agree on a payment method with 93% of the creditors. While the remaining 7% were defined by the lack of agreement and were in litigation with Argentina, which caused our country to be left out of the formal international capital market.
Consequently, the mechanisms for financing the treasury's fiscal deficit were reduced to: typical tax pressure, inflation tax, or placement of domestic debt.
Thus, one of the issues the incoming government had to resolve was ending the technical default . In practice, this meant seeking a definitive solution to the conflict with the remaining 7%, the so-called vulture funds (or holdouts ). Once in office, the new economic team quickly began these negotiations.
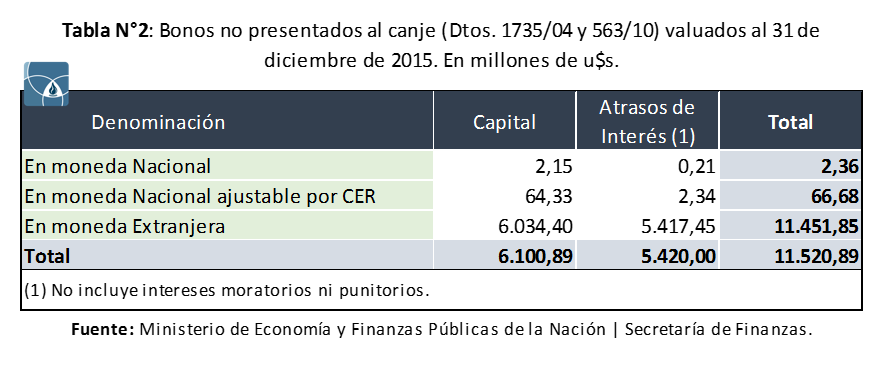
The debt with these funds at the end of 2015 was just over 11.500 billion dollars, which represented 45% of the BCRA's dollar reserves, valued at the value of the official nominal exchange rate of that date ($13,005/u$ s), and without including penalties.
On February 3, 2016, Minister Prat-Gay announced a preliminary agreement with a group of Italian bondholders for $1.350 billion. Then, on February 5, the economic team of the Ministry of Finance and Public Credit presented a restructuring offer to all creditors who had not participated in the 2005 and 2010 debt swaps. Two types of proposals were made: a base offer and a pari passu offer.
From a legal point of view, it was necessary for Congress to repeal a couple of laws that prevented payment to these litigating funds ( lock-out law and sovereign payment law ).
The National Congress repealed both laws in the early hours of March 31, and the following day, the Government enacted the law for payment to the holdouts (Law 27.249), enabling the national executive to sell bonds on the market to cancel the defaulted debt.
Starting the month of April without internal legal impediments and with more pre-agreements reached, eyes shifted to waiting for the decisions of the North American justice system.
On April 13, the Second Circuit Court of Appeals in New York announced its decision to uphold the lifting of the precautionary measures ordered in the first instance by Judge Griesa, which had prevented Argentina from paying its obligations.
After these precautionary measures were lifted, on Monday, April 18, the state went to the market to obtain the funds by offering different types of bonds. The next day the operation was closed with an issue of 16.500 billion dollars
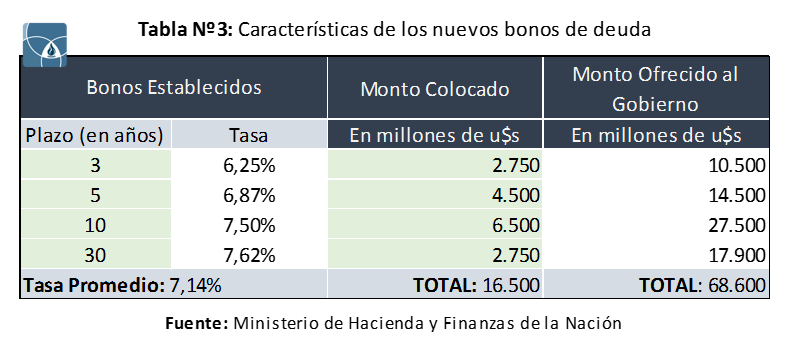
This was a figure greater than the 12.500 billion dollars that the National Congress had authorized. So, in order to exceed the amount, the Executive allowed, through decree 594/2016, the Treasury to take on debt under foreign jurisdiction, for 10 billion dollars. It was agreed between the parties that payment would be on Friday, April 22; beginning, therefore, a new stage.
The Argentine case was emblematic for its magnitude, and went through different stages: arduous negotiations with investment banks, two debt swaps with haircuts, and a long path of litigation, all due to the international legal vacuum and the contracts.
Externally , new codes of conduct between creditors and debtors were established by the International Capital Market Association (ICMA). Furthermore, Argentina achieved a diplomatic victory at the UN with the adoption of nine principles to guide debt restructurings.
Regarding re-entry into international financing markets, it can only be considered an advantage, in the sense that it is beneficial for a country to have a greater number of options, even if these are not used. The doubt lay in what costs should be assumed to achieve this goal. However, once the decision was executed, these costs sank, giving rise to a new stage still undefined.
In economics, we call sunk costs those costs that have already been incurred, and therefore cannot be recovered, which is why they should not affect future decisions. For example, if a person buys a movie ticket online, that past action should not affect the decision to go see the movie. Suppose that that same day and time another plan arose: to go to a recital. If this were the scenario, the cost of the ticket should not influence the decision, since it has already been spent, regardless of what is done.
Whats Next?
If the entry of new capital helps to improve the level of reserves, to stabilize the exchange rate, and has a positive impact on the real economy, without harming the maintenance of the debt; By definition, the benefit will be positive.
On the other hand, if the opening of the stocks accelerates the flight of foreign currency in the long term, new pressures are generated against the exchange rate, the financial flow does not translate into real investment flow, or a new debt spiral is entered; then the result will be the opposite.
In our full report , which is available for download, we provide a more in-depth analysis of the points raised, as well as a comparative analysis with other Latin American and developed countries regarding the interest rates they pay when issuing bonds. We invite you to read it.