

Why did the price of soybeans rise more than 10% in June 2015 if an oversupply was expected, and what do expectations and the futures curve show? Note from July 2015.
In the last two weeks, the price of soybeans reversed the downward trend it had shown since the middle of last year. It experienced a strong recovery : closing the week at USD 383 per ton, compared to USD 347 at the beginning of June. In other words, an increase of more than 10% was recorded in just one month.
This sharp increase in soybean prices presents an excellent opportunity to better understand how international financial markets operate , using a practical example highly relevant to the Argentine economy. Why did the price of soybeans rise? Let's review some key concepts and indicators.
Global supply and demand for soybeans
The first thing economists are tempted to do is review soybean supply and demand indicators . Regarding the former, we take the estimate made by the United States Department of Agriculture on June 10th. According to this estimate, global soybean production would reach 318,3 million tons (MT) in the 2014/15 season. This is the season that is currently concluding in South America.
On the other hand, total consumption would be 294,0 MT, resulting in an increase of almost 21,0 MT in grain inventories.
Likewise, the outlook for the upcoming season is less encouraging. The projected supply is 317,6 million metric tons (MT), 13 MT above demand. This would push soybean stocks to a record high of 93,2 MT. Therefore, initial indicators suggest that prices are likely to trend downward in the medium term.
Financial markets and the price of soybeans
How is it possible, then, that we are seeing a price increase with these prospects of oversupply? The first point to consider is how financial markets work.
In these markets, prices tend to be especially volatile in response to news that alters the economic outlook. We often see stock market indicators react (or overreact) to certain news items, which are expected to change future events in some way.
Now, the first thing to understand when following asset prices in financial markets is that they depend fundamentally on expectations.
That is, the price of an asset depends largely on what the market (the average of buyers and sellers) believes it may be worth in the future. This is why prices react strongly to any indication of what may happen in the near future.
When new economic data emerges, markets incorporate new information into their assumptions about its evolution, and in this way they revalue their assets.
For example, a company that sells a consumer good in the United States depends crucially on the evolution of economic activity in this country. That is why news that shows that unemployment has decreased will tend to increase its contribution.
How much does the surprise of a news story weigh?
Another point to consider is that the impact of this news will largely depend on how different the new situation is from what the players had already anticipated. In other words, the more surprising the news , the greater the effect it will have.
For example, if everyone expects the economy to recover, this expectation will be factored in when valuing assets. In other words, their value will be calculated taking into account that the economy will be more dynamic in the future.
Conversely, when it is confirmed that activity is already showing positive trends, the impact will be less significant. This is because it was already factored in by market participants. The same applies when the level of activity is unfavorable, although in the opposite direction. The reaction will be a drop in the prices of major assets (at least those most critically dependent on the level of activity).
The biggest drops usually occur when the market forms overly optimistic expectations for a long time, which is commonly known as a bubble . Ironically, even good news can end up having a negative impact on prices if it isn't as good as initially expected.
For example, if an economy minister announces a drop in the level of unemployment, the impact can be negative if that reduction is not as large as the markets initially expected.
Bubbles and why they are hard to detect
Economic bubbles are phenomena that manifest themselves as a considerable gap between the discounted price of an asset and its intrinsic value.
The first difficulty in detecting them early is that, initially, both valuations are—for all practical purposes—the same. The other difficulty—more fundamental—is that, to date, there is no consensus on their causes. Indeed, especially in the cases of bubbles that triggered major crises, some authors suggest that they are unique rather than systematic.
What happened to the price of soybeans?
Returning then to the initial example: what has happened to the price of soybeans? That the latest news projects that perhaps next season's harvest will not be as good as expected.
Does this mean there will be a shortage or that demand will once again outstrip supply? Definitely not. The outlook remains for a significant soybean surplus on the global market . The difference is that this surplus is no longer as large as was expected a few months ago.
A clear example of this adjustment mechanism can be seen in what happened between the last two reports published by the United States Department of Agriculture. In May, soybean stocks at the end of the 2015/16 season were estimated to reach 96,2 million metric tons (MT). By June, the estimate had been revised downward to 93,2 MT.
This stock level represents an 11,4% increase compared to the previous season (which would culminate in a 33,3% increase in inventories). Even so, prices reacted positively between the two reports. This is because, with the new information, the soybean surplus in the markets is expected to be lower than anticipated.
Climate and the futures curve
The ultimate explanation for the revised projections is that, in recent days, the weather has taken on a decisive role in price trends. The persistent rains observed in some of the most important producing regions of the Northern Hemisphere suggest that average crop yields may be lower than expected.
In this regard, it's interesting to observe the changes in the futures curve . The latest news shifted the entire curve upward. That is, both the current price of the oilseed and the options to buy in a few months, or next year, increased. However, the effect wasn't uniform.
While the current price grew by almost USD 40 per ton in a few weeks, the effect on the future price was less: for September 2016, a soybean price of USD 362 per ton is projected, less than 10 dollars above what was expected.
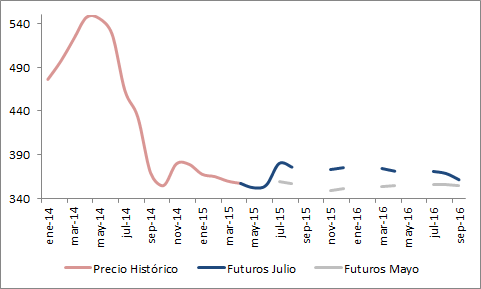
Precio histórico de la soja y curvas de futuros de mayo y julio.Why is the impact different? Because the latest news changed expectations regarding the 2015/16 production in the Northern Hemisphere, which enters the market in the second half of 2015. But it did not change the forecasts regarding production in the Southern Hemisphere, which would only be available in mid-2016.
This illustrates the complexities involved in analyzing prices in agricultural markets . It's not just the supply that matters, but also when that supply becomes available. This is yet another variable that must be considered when making projections.
Open access, for use and citation
The report is available freely and without charge, under a Creative Commons license (CC BY-NC-SA 4.0):
- 📄 Full report (PDF): Download the report
- 🗄️ UNR Hypermedia Repository (RepHip): https://hdl.handle.net/2133/14508
- 📚 More reports from the Observatory: Index of Reports
Apuntes para analizar el precio de la soja. Informes del Observatorio UNR N.º 9 — Serie Puente Académico N.º 2, julio de 2015. ISSN 2683-9067 / 2683-9091. Autor: Germán A. Tessmer.