

Ten questions to understand what the real exchange rate is, how it is set by the market or the government, and who wins and loses with a devaluation. February 2016 report.
The new government's decision to unify the exchange rate resulted almost immediately in a depreciation of the Argentine peso.
As expected, the measure generated significant media coverage and social networks. Opinion pieces on the matter proliferated, both for and against the measure.
Our article arises in response to two major shortcomings found in most of these notes and opinions. We believe these shortcomings undermine a pluralistic understanding of economics among the population.
The first is that a large amount of the material presents devaluation as entirely dependent on a political decision. There is no mention whatsoever of market forces that can force variations in the exchange rate, even against the will of the rulers.
The second is the tendency, especially common among Argentinians, to highlight only the advantages or disadvantages of the economic policy decision. It all depends on the perspective of the author of the news article.
What are we looking for with these ten questions?
In this article, we will focus on answering 10 questions to understand which variables and events impact the exchange rate . We will also examine the expected effects of a devaluation. We will attempt to clarify the issue in a straightforward manner. Our goal is to help our readers refine their opinions by weighing the costs and benefits of the measure from a technical perspective. We hope this will complement the subjective or ideological assessments of each individual.
On the one hand, we will see that the path the exchange rate takes in an economy depends on the—let's call them—invisible forces of the capitalist system. Furthermore, while many mechanisms exist to counteract these forces, it is not always easy to go against them.
Secondly, it will be clear that, like almost all economic policy actions, the consequences can hardly be classified in their entirety as “positive” or “negative.”
Whether the result is a high or low exchange rate, whether an interventionist policy is implemented or the price is left to the market, whether devaluation occurs through a shock or gradually, all these measures create winners and losers, as well as having positive and negative consequences in the short and long term.
The final assessment of economic policy will depend on each individual's personal evaluation of the importance of each economic sector, or of short-term versus long-term considerations. We believe that understanding each of the consequences is crucial for forming a responsible opinion.
1-What are the nominal exchange rate and the real exchange rate?
The exchange rate itself indicates the price of one currency measured in the local currency. In other words, the rate at which the two currencies are exchanged.
The most common way to measure the exchange rate is bilaterally against the US dollar. This currency is considered the international reserve currency. Thus, a higher exchange rate means that more pesos will be needed to obtain one dollar.
However, and contrary to common sense, this type of exchange is not the most relevant when determining economic policy. First of all, because the value of the dollar varies with respect to other currencies.
For example, in the last year most countries strongly depreciated their currencies against the dollar. Being tied to the value of the North American currency in this context implies that the Argentine peso gains value with respect to -for example- the Brazilian real.
Strictly speaking, when there are free floating or managed floating exchange regimes (like ours), the correct term to indicate that the local currency has lost value against a currency is “depreciation”. However, the force of use and custom ended up imposing the term “devaluation.”
Nominal exchange rate and real exchange rate
A crucial concept often overlooked when discussing the nominal exchange rate —the rate reported daily on the news and familiar to virtually every adult Argentine—is that it doesn't determine the economy's competitiveness. The relevant index for national production is the real exchange rate.
To easily differentiate them, it can be said that the nominal exchange rate shows the price of the foreign currency expressed in the local currency, while the real exchange rate serves to compare the prices of a basket of goods produced in our country with respect to the rest of the country. world. The formula is simple to understand:
- e = real exchange rate
- E = nominal exchange rate
- CPI = local price index
- CPI = price index of the rest of the world
In other words, the real exchange rate is what tells us whether local products are cheap or expensive compared to the rest of the world. In this way, when the real exchange rate falls, it means that local products become more expensive compared to those from the rest of the world, therefore it will be more difficult to compete with other countries.
The usual consequence is a reduction in exports and an increase in imports. The opposite occurs when the real exchange rate rises.
What does the real exchange rate depend on?
The real exchange rate basically depends on three variables. The first is the nominal exchange rate. The second is local inflation and the third is inflation in the rest of the world.
For the real exchange rate to remain stable, that is, for the economy neither to lose nor gain competitiveness, the depreciation of the currency must be equivalent to the difference between local inflation and that of the rest of the world.
To give a simple example, if the depreciation of the Argentine peso is 15% per year, but inflation is 20 percentage points higher than that of the rest of the world, it means that the economy is losing competitiveness. Even though the Argentine peso is worth less and less against the dollar, the dollar prices of local goods are increasingly higher.
Thus, we arrive at the first conclusion : if an economy has a very high inflation rate, it is also likely to have a high rate of currency depreciation, in order to avoid a relative increase in the price of the goods it produces. In other words, not only does currency devaluation generate inflation, but inflation also generates devaluations.
To give an example in terms of the formula we saw earlier, suppose the local price index [CPI] increases by 20%. The nominal exchange rate [E] should increase (depreciate) by another 20% in order not to affect the level of the real exchange rate [e]. It should be noted that in this example we assume that the price index for the rest of the world [CPI] remains constant.
2-How is the exchange rate of an economy determined?
The first thing to consider is that the nominal exchange rate is a price . Therefore, it is determined in the same way as all prices in the economy: by supply and demand.
Of course, in this case, supply and demand are very specific. But the mechanism by which the exchange rate is determined is very similar to that of the price of any good.
If there are more people who want to buy dollars than those who want to sell, the price of the dollar rises. Otherwise, if there are more people who want to sell than people who want to buy, the price of the dollar falls.
What needs to be analyzed then is how many people want to exchange their pesos for dollars and how many dollars enter the economy to be converted into pesos.
Who sells dollars?
- Exporters, who sell their products abroad, obtain dollars and enter them into the local economy.
- Foreign investors who buy assets in pesos locally. This includes everything from the purchase of a local company to a loan in dollars obtained by the government or any private individual, including sales of dollars for pesos that are carried out through home banking.
- Foreign tourists.
Who buys dollars? As you might expect, in this case the relationship is reversed. Importers who need to pay for goods brought in from abroad and people who buy foreign assets, whether dollars themselves, stocks, or bonds, buy dollars. Tourists traveling abroad also buy dollars.
The equilibrium exchange rate
What's important to understand is that, left to its own devices, the exchange rate will automatically fluctuate to balance these forces. It will do so until the amount of dollars people want to sell is exactly equal to the amount they want to buy. Let's suppose, for example, that there is excess demand for dollars in the economy.
In that case, the price of the dollar, the exchange rate, will rise. As a result, many people will decide to buy fewer dollars, either because they consider it too expensive or simply because the same amount of pesos equals fewer dollars.
The effect operates primarily in the medium term, impacting both exporters and importers in the same direction. A currency depreciation makes foreign products more expensive, reduces imports, and boosts exports.
The exchange rate that the market determines on its own is usually called the equilibrium exchange rate . It's worth noting that this doesn't always coincide with the exchange rate at which the economy is actually operating. It's like a kind of attractor point, a place toward which the economy converges.
This leads us to our second conclusion : market forces always seek to balance the supply and demand for foreign currency. In doing so, they bring the exchange rate to its equilibrium level. Consequently, bypassing these mechanisms and setting a different exchange rate, while feasible, is not always easy.
Next, we will examine what happens when you try to change this price.
3-Can a government set levels other than the equilibrium exchange rate? As?
Yes, the exchange rate at which the economy operates is not always the equilibrium rate. The government can set different levels through two generic mechanisms, which are quite easy to understand.
The first is by intervening directly in the supply and demand of foreign currency. This measure is commonly used by almost all central banks worldwide, especially to prevent excessive exchange rate volatility. The consequence of this intervention is a change in international reserves.
If the Central Bank wants to prevent the exchange rate from rising , it should intervene by selling foreign currency at the target price. In other words, it should cover the difference in the number of dollars that economic agents are trying to acquire at the current price but cannot due to a lack of supply.
As a consequence, there will be a reduction in the Central Bank's international reserves (now held by the public). There will also be a decrease in the amount of money circulating in the economy (since it is being purchased by the Central Bank).
Conversely, if the Central Bank wants to prevent the currency from appreciating, it should buy dollars. This increases its international reserves, but also the money supply.
The role of international reserves
This is the primary role of the Central Bank's international reserves . They allow the bank to intervene in the foreign exchange market and prevent sharp depreciations. It should also be clear that, contrary to what many people believe, perhaps due to the experience of the convertibility plan of the 90s, an economy's equilibrium exchange rate cannot be calculated simply as the ratio between the amount of dollars held by the Central Bank and the amount of pesos in circulation.
Even without international reserves, the exchange rate can depreciate if supply and demand dictate it. In other words, not having reserves doesn't mean the exchange rate will necessarily rise. But it does mean that if market forces cause it to rise, the Central Bank will be powerless to prevent it.
An even more disturbing thought: the amount of money in the economy is always greater than the amount printed on paper. This is due to what is known as the money multiplier.
Thus, even if the bills are equivalent to the amount of dollars held by the largest banking entity, it is possible that it will not be able to withstand a run against the peso. This explains why even with the convertibility law, currency depreciation ended up being inevitable.
Restrictions on trade and capital
But we still need to describe the second mechanism the government has to prevent exchange rate fluctuations. This simply involves restrictions on foreign trade , specifically the inflow and outflow of capital.
If the government wants to avoid currency devaluation, it can reduce the demand for foreign currency. To do this, it can impose taxes or prohibitions on both imports and capital outflows.
This is what has been sought in recent years through the application of the DJAI, restrictions on the transfer of dividends abroad, or simply the exchange rate.
Conversely, if the aim is to avoid currency appreciation , the most common measures are restrictions on capital flows and the application of export duties.
An important clarification on the last point: the application of export duties used to prevent currency appreciation loses much of its effectiveness if the government spends the resources it collects with that tax, since in that way the dollars also end up being converted into pesos.
It is for this reason that this type of policy is usually accompanied by the creation of investment funds abroad or debt relief policies.
4-Can these levels be maintained forever?
No. Or at least, it's difficult.
What happens if the government insists on avoiding devaluation, that is, keeping the exchange rate below equilibrium? If that were the case, the Central Bank would be continuously losing reserves.
In other words, the amount of international reserves held by the entity limits the duration of the low nominal exchange rate policy.
Faced with this dilemma , some governments commonly resort to foreign loans to bolster their reserves. However, if there are no changes in the productive (or financial) structure that alter the equilibrium exchange rate (for example, an increase in exports), these actions represent only a temporary solution.
However, these types of loans sometimes end up being effective, because the signal of a Central Bank with a higher level of reserves can discourage financial speculation, since expectations of depreciation are reduced, and therefore the demand for assets denominated in foreign currency falls in anticipation of a devaluation.
On the other hand, maintaining the exchange rate above its equilibrium level is easier in the medium term. But even so, it's difficult to do so indefinitely. In this case, the Central Bank must buy foreign currency and provide pesos in exchange. The result is an increase in the amount of money circulating in the economy.
Generally, this causes an increase in the price level, thereby reducing the real exchange rate. Thus, the adjustment ends up being carried out not through a devaluation, but through higher inflation.
Money supply and price level
The causes of inflation and the relationship between the money supply and the price level are topics that require even more discussion than the determination of the exchange rate. Opinions on the subject range from those who believe that the relationship between prices and the money supply is practically direct, to those who deny that any causality exists.
The most widely accepted view is that -in most cases- a significant increase in the monetary base (understood as an exogenous shock) would cause an increase in prices.
This does not imply that there are no cases in which an increase in the money supply can be absorbed by variations in the rate of circulation of money or the product, nor that any price variation is explained exclusively by changes in the monetary base.
However, it is a much slower process, and it can be delayed even more if the Central Bank compensates for this increase in the monetary base by reducing the amount of money in the economy through some other means, for example, by selling bills.
In this case, the disadvantage is that this type of asset involves paying an additional amount in interest. Therefore, the Central Bank could incur a deficit.
5-What advantages and disadvantages does the high exchange rate have? Who wins and who loses?
The advantage of a high exchange rate is that it makes the economy more price-competitive . This, in turn, benefits domestic production. This is because producers of tradable goods (those that can be exported and imported) have a greater opportunity to sell their production abroad.
On more than one occasion a government has used a high exchange rate to promote the growth of national industry.
The downside is that wage earners are harmed , at least in the short term, because wages in dollars are kept artificially low. In other words, the competitiveness gained is based primarily on paying lower wages.
Among the various productive sectors, those that benefit most are those that can export their production. Becoming more competitive allows them to increase their output. But even if they don't export, the possibility of earning income in foreign currency at artificially low costs improves their business profitability.
In fact, the most competitive sectors of the economy obtain extraordinary profits from maintaining this policy.
Conversely, sectors that sell only their production in the domestic market are negatively impacted. This is because lower wages lead to reduced consumption. Consequently, service providers (non-tradable goods and services) are among the hardest hit.
6-What advantages and disadvantages does the low exchange rate have? Who wins and who loses?
Contrary to what happened with the high exchange rate, an artificially low exchange rate reduces the price competitiveness of the economy, harming the producers of tradable goods, who suffer a decrease in their profitability and, sometimes, even have to reduce its production.
On the other hand, wage earners improve their purchasing power, especially for goods that are not produced locally. In this way, many governments tend to fall in love with the idea of a low exchange rate, since it favors a better standard of living for the population, which also translates into better electoral results.
As mentioned above (but in the opposite sense), producers of non-tradable goods benefit from this increase in the purchasing power of the population.
Another reason to keep the exchange rate low, or rather, to avoid devaluations, is the possibility of using it as an anti-inflationary anchor.
In high inflation economies, a devaluation could encourage this problem, so it is normal for governments to decide to let the exchange rate appreciate rather than run the risk of prices skyrocketing. Of course, this is a temporary solution.
Industry facing devaluation
One point in particular deserves more detailed discussion here. On many occasions, industrial producers are against devaluations, even when their production is technically exportable.
This occurs when the goods made by these sectors are sold mainly in the domestic market, so the negative impact that the devaluation has on real wages (due to the increase in the prices of imported products) translates into lower demand.
Thus, a devaluation can be highly contractionary (in fact, it usually is in the short term). This occurs because it harms not only service providers but also industry.
However, something that is not usually discussed is that for this to happen, the economy must have a somewhat unbalanced productive structure.
Free competition and protection
Let's do the exercise of thinking about a scenario of free competition: although the devaluation would reduce domestic demand, the industry could benefit from less competition from imported products (which become more expensive) or from the possibility of starting to export.
Thus, after the initial negative shock, given that you cannot start exporting from one day to the next, the final net effect can be positive for the sector.
But this wouldn't be the case if the industry relies on import restrictions. This is because these restrictions already eliminate foreign competition, so there's not much to gain from a currency depreciation.
The possibility of exporting would also not be available, because industries that require protection to sell domestically are usually very far from being able to compete in international markets.
In summary , while a currency devaluation initially harms the industry, the medium-term impact depends on the level of protection. Industries that survive thanks to restrictions on competition are negatively affected in the long run. Conversely, others can improve their situation through increased competitiveness.
7-Does this mean that the exchange rate set by the market is always the best option?
Not again. As can already be deduced from the article, there are no absolute answers in economics, nor permanent measures. Everything depends on the context or, even more so, on each particular situation.
To illustrate, we will mention some specific cases where intervention in setting the exchange rate may be quite convenient. This does not preclude other situations where it may also be desirable; we will only mention the most common ones here.
1. Capital markets exhibit high volatility: that is, the inflow and outflow of financial funds seeking to arbitrage prices and capture short-term profits. In such cases, it is logical to expect temporary intervention to stabilize the exchange rate and smooth out fluctuations.
2- Capital markets drive the exchange rate to a level that does not (and will not) correspond to the country's productive and export development: it may happen that a constant inflow or outflow of capital leads the exchange rate to an equilibrium in which the trade balance is heavily in deficit, for example.
The above can lead to a problem, since the exchange rate is being set too low for the survival of local businesses, even when the supply and demand for foreign currency are in equilibrium. This generally occurs when large amounts of foreign currency enter the country through privatizations, loans, or speculative investments, which then fail to translate into improved productivity for the economy.
Unbalanced economies: the Dutch disease
3- The economic structure is unbalanced, and there is a desire to develop a sector that is not competitive at the current exchange rate. This generally occurs in countries rich in natural resources.
Exporting these resources generates significant foreign exchange earnings and reduces the exchange rate. This makes it more difficult for other industries to compete internationally.
If there is any reason why you want to develop these other industries, one possibility is to differentiate the exchange rate into two, which can be done by setting a double exchange rate or through specific taxes on the exploitation of natural resources (such as case of export duties).
This latter phenomenon is known as Dutch disease . It is worth noting that the mere existence of abundant natural resources has led to interventions of this kind, justified by this theory.
However, to justify a differentiated exchange rate, it is also necessary to explain why it is desired to develop this other type of activity, instead of letting the economy run its course and specialize in the exploitation of natural resources.
There is generally consensus on combating the Dutch disease when the appreciation is temporary (for example, the price of the good being exported takes on unusually high values), but justifying this type of policy as a measure for development is a little more difficult.
An overly indebted economy
4- The economy is over-indebted. If the country is too heavily indebted in foreign currency, a devaluation could lead to a breakdown in payment chains, generating bankruptcies and crises.
Maintaining an overvalued exchange rate indefinitely is far from solving this problem. But if this situation can be reversed in the not-too-distant future, it seems sensible to avoid an unnecessary crisis.
8-How has the real exchange rate evolved in Argentina in recent decades?
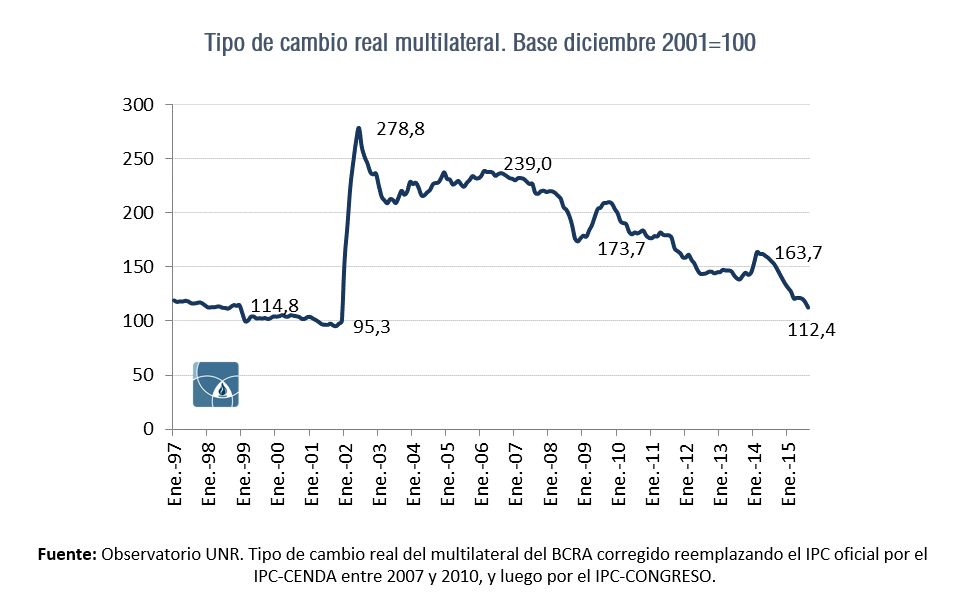
Sometimes a picture is worth a thousand words. The following graph shows how the real exchange rate increased after the 2002 devaluation. But it then appreciated again due to inflation and the Brazilian currency devaluation starting in 2008.
A quick glance at the chart reveals two interesting points regarding our history. The first is that the real exchange rate of our economy in December 2015 is at levels similar to those recorded during the last period of convertibility.
Second, and something that has already been pointed out in previous articles, the level of the real exchange rate that functioned as one of the pillars of the model - plain and simple - of the previous administration was a high one.
9-Why have different types of exchange emerged in recent years?
To prevent currency depreciation, the outgoing national government implemented controls on foreign currency purchases. However, many individuals still wanted to acquire foreign currency at a higher rate than that set by the Central Bank. This led to the creation of a parallel or black market for foreign currency.
Among the different measures that were adopted, is the much discussed exchange rate trap.
10-What prices are expected to show an increase after unification?
In the event of a devaluation, the prices that fluctuate the most are those of commodities. That is, those whose price is fixed in dollars on the international market. This is why grains, milk, meat, oil, and minerals show sharp increases.
In Argentina, the result is that the prices of products that are produced internally, such as some foods, increase even more rapidly than goods with a high imported component, something that is not fully understood by the common population.
Taking out commodities, those products that have a greater imported component will show a greater price variation. Services, being non-tradable, would show the smallest increase.
Open access, for use and citation
The report is available freely and without charge, under a Creative Commons license (CC BY-NC-SA 4.0):
- 📄 Full report (PDF): Download the report
- 🗄️ UNR Hypermedia Repository (RepHip): https://hdl.handle.net/2133/14520
- 📚 More reports from the Observatory: Index of Reports
10 preguntas para entender las variaciones del tipo de cambio. Informes del Observatorio UNR N.º 19 — Serie Puente Académico N.º 5, febrero de 2016. ISSN 2683-9067 / 2683-9091. Autor: Germán A. Tessmer.